Добро пожаловать на официальный сайт Национального банка Молдовы!
×
У вас хорошее зрение, и вы хотите отключить этот инструмент?


Добро пожаловать на официальный сайт Национального банка Молдовы!
Вы можете выбрать один из наиболее востребованных отчетов из списка:
Национальный банк и члены его руководящих органов независимы в осуществлении своих функций, установленных настоящим законом, и не могут обращаться за указаниями и получать таковые от органов публичной власти или какого-либо иного органа.
Стратегия денежной политики НБМ на среднесрочный период предусматривает поддержание количественного объектива инфляции на уровне 5.0% с возможным отклонением ± 1.5 процентных пункта – оптимальный уровень для устойчивого экономического роста и развития Республики Молдова на среднесрочный период.
Национальный банк обладает исключительным правом эмиссии на территории Республики Молдова банкнот и монет в качестве платежного средства.
Национальный банк обладает исключительным правом лицензирования, осуществления надзора и регулирования деятельности финансовых учреждений.
Национальный банк имеет право покупать, продавать и негоциировать иностранную валюту, используя активы, покупать и продавать казначейские обязательства и другие ценные бумаги, выпущенные или гарантированные правительствами иностранных государств и международными финансовыми публичными организациями.
Национальный банк осуществляет надзор за системой платежей в республике и способствует стабильному и эффективному функционированию автоматизированной системы межбанковских платежей.
Национальный банк является самостоятельным публичным юридическим лицом и несет ответственность перед Парламентом.
Национальный банк информирует общественность о динамике годовой инфляции, о стратегии денежной политике, результаты макроэкономического анализа, анализа развития финансового рынка и статистическую информацию, в том числе относительно денежной массы, предоставления кредитов, платежного баланса и положения на валютном рынке.
Национальный банк проводит экономический и денежный анализ, составляет платежный баланс, международную инвестиционную позицию и разрабатывает статистику внешнего долга Республики Молдова.
As of 30 June 2026, there were 9 insurance companies operating in the Republic of Moldova (of which 8 were engaged solely in general insurance and one composite company was active in both the “non-life insurance” and “life insurance” categories), 58 insurance and/or reinsurance brokers, 48 insurance agents and 34 bancassurance agents.
At the end of the first half of 2026, the insurance sector was characterised by an increase in assets, capital and technical provisions compared to the end of the previous quarter. Gross written premiums and claims paid during the first half of 2026 increased compared to the same period of the previous year. The average solvency ratio per sector for non-life insurance has increased compared to the situation on 31 March 2026, while the solvency ratio for life insurance is declining. The average liquidity ratio for both non-life and life insurance is decreasing compared to the end of the previous quarter. The net profit increased significantly compared to the same period of the previous year and the combined operating ratio decreased compared to 31 March 2026. All insurance companies reported profits from their activity during the first half of 2026.
At the end of the first half of 2026, the financial situation in the insurance sector, as reflected in the reports submitted by professional participants in the insurance market, showed the following trends:
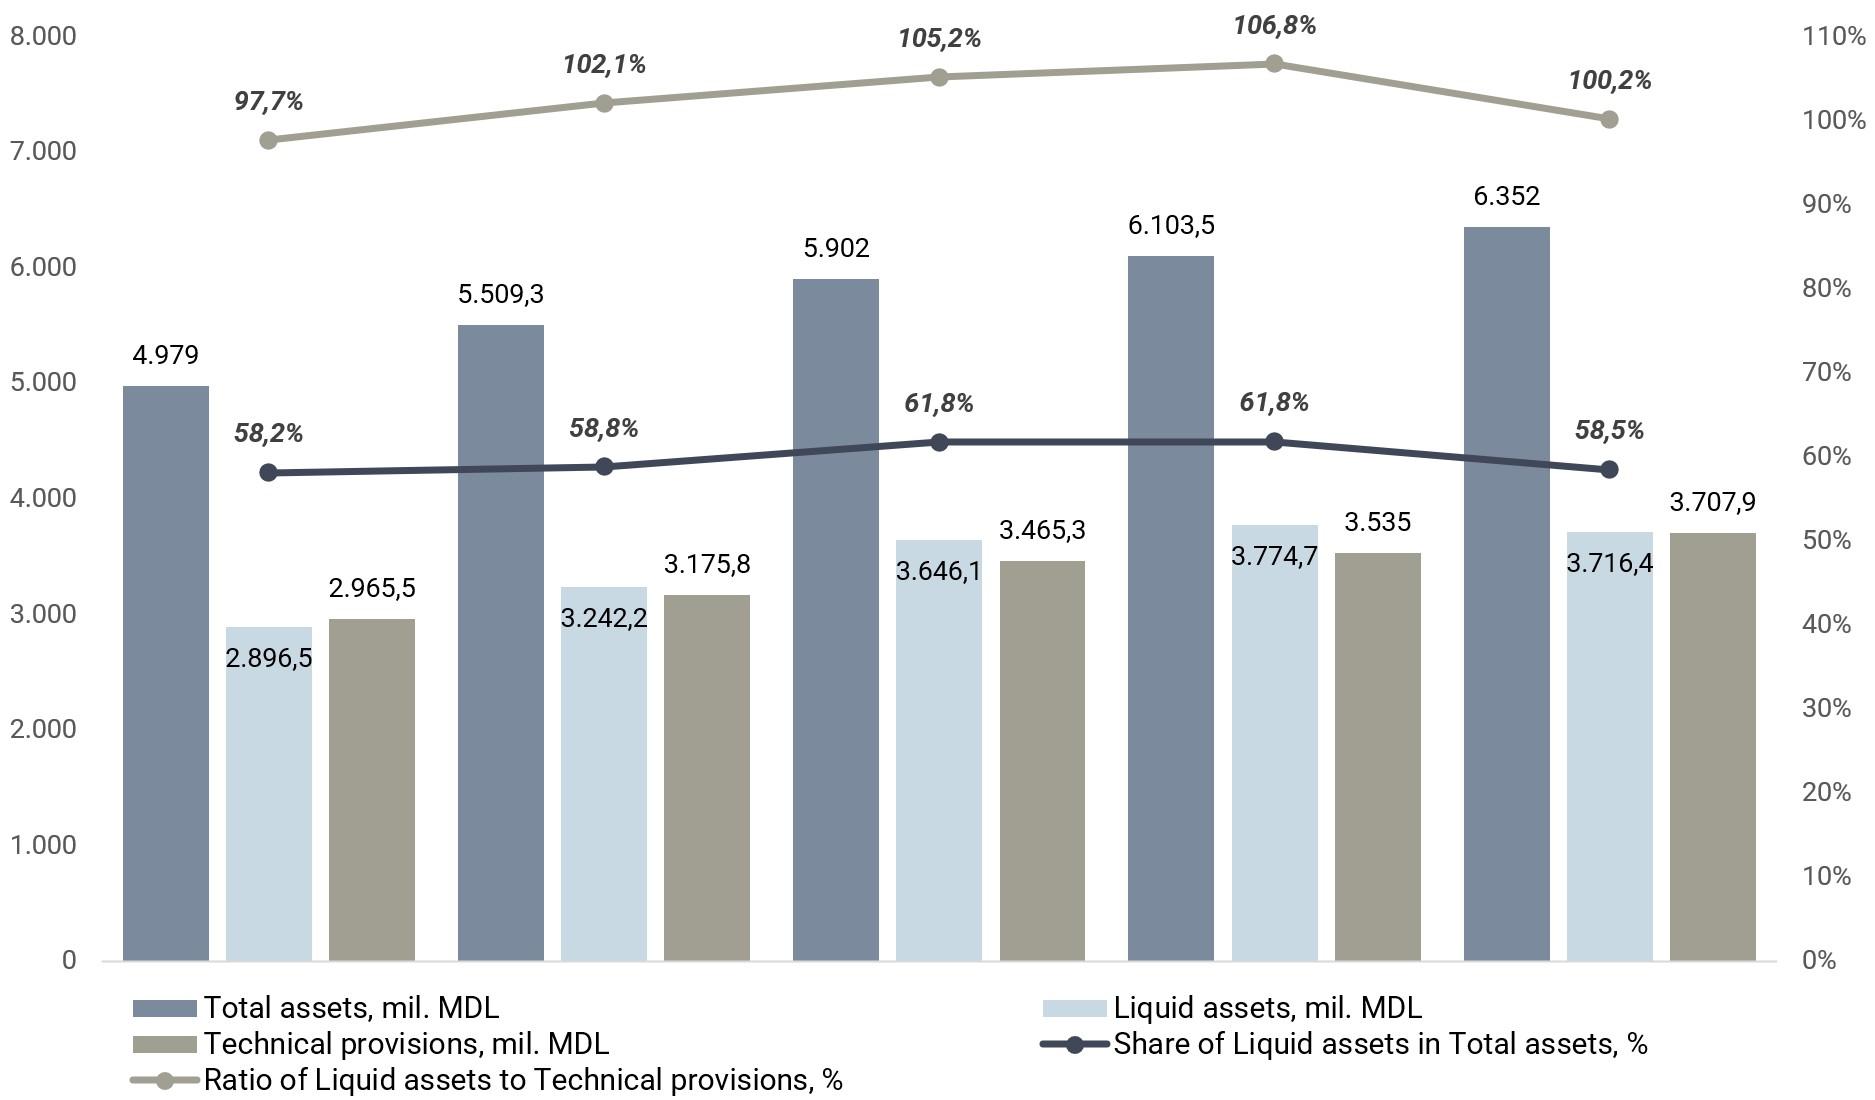
The total assets of insurance companies at the end of the first half of 2026 amounted to MDL 6 352 million, an increase of MDL 248.5 million or 4.1 % compared to 31 March 2026. The value of liquid assets amounted to MDL 3 716.4 million, down by MDL 58.3 million or 1,5 % from the previous quarter, which represents 58,5 % of the total assets reported by insurance companies. The value of liquid assets in relation to the value of the total technical provisions in the market was 100,2 %.
Chart No 1 Evolution of assets recorded in the insurance sector
All licensed insurance companies reported solvency ratios above 100 %. The average solvency ratio for non-life insurance activity has increased by 3,8 percentage points compared to the end of the previous quarter and amounted to 167.6 %, with insurance companies reporting solvency ratios between 131.3 % and 201.1 %. A solvency ratio of 620,8 % was reported for life insurance, down 23,3 percentage points from the value reported on 31 March 2026.
As of 30 June 2026, the eligible own funds of insurance companies amounted to MDL 1 515.6 million, an increase of MDL 55.1 million or 3.8 % compared to 31 March 2026. For non-life insurance activity, own funds totalled MDL 1 266.6 million, an increase of MDL 63 million or 5,2 % compared to 31 March 2026, and for life insurance, own funds amounting to MDL 249 million were reported, MDL 7.9 million or 3,1 % less than at the end of the previous quarter.
At the reporting date, all insurance companies had liquidity ratios higher than 1 for each category of insurance, varying for non-life activity between 1,12 and 4,71. On average, the liquidity ratio for non-life insurance activity decreased by 0,24 points compared to the end of the previous quarter (from 3,56 to 3,32), while for life insurance a decrease of 0,5 points (from 15,39 to 14,89) was reported.
As of 30 June 2026, insurance companies had established gross technical provisions totalling MDL 3 707.9 million, an increase of MDL 173 million or 4.9 % compared with the end of the previous quarter, broken down into the two categories of insurance as follows:
• the gross technical provisions established for non-life insurance recorded a volume of MDL 2 734 million, representing 73,7 % of the total technical provisions;
• for life insurance, technical provisions amounting to MDL 973.9 million were established, with a share of 26,3 % of the total technical provisions.
Technical provisions for non-life insurance activity increased by MDL 169 million or 6,6 % compared to the situation on 31 March 2026, resulting from the increase in all types of reserves, namely the increase in unearned premium reserves (UPR) by MDL 62,4 million or 4,2 %, the increase in unexpired risk reserves (URR) by MDL 47,6 million or 38,7 %, the increase in reported but not settled claims reserves (RBNS) by MDL 47,3 million or 8,5 % and the increase in claims incurred but not reported claims reserves (IBNR) by MDL 11,8 million or 3,0 %.
For non-life insurance, significant shares in the composition of gross technical provisions are held by the unearned premium reserves (UPR) - 56,6 %, down 1,3 percentage points from 31 March 2026, and the reported but not settled claims reserves (RBNS) - 22,2 %, up 0,4 percentage points from 31 March 2026.
In the case of life insurance, gross technical provisions amounting to MDL 973.9 million were formed, MDL 3.9 million or 0,4 % more than at the end of the previous quarter. The largest share of provisions (89,8 %) consists of the mathematical and additional mathematical provisions, more than 0,6 percentage points compared to 31 March 2026.
As of 30 June 2026, the total value of admitted and final distributed assets to cover technical provisions and the minimum capital requirement amounted to MDL 4 862.2 million, the surplus of assets after covering technical provisions and the MCR amounted to MDL 667.8 million.
According to the reports submitted, all insurance companies held sufficient assets to cover technical provisions and the minimum capital requirement, taking into account the restrictions set out in the legislation. The most important asset categories allowed and finally distributed by companies to cover technical provisions and the minimum capital requirement were distributed as follows: government bonds – MDL 3 302 million or 67.9 % of the assets covering technical provisions and the minimum capital requirement, the reinsurer’s share – MDL 736 million (15.1 %) and deposits – MDL 327.7 million (6.7 %).
During the first half of 2026, insurance companies wrote gross premiums in the amount of MDL 1 778.3 million, which is MDL 185.3 million or 11,6 % more than the gross written premiums during the similar period of the previous year.
As in previous years, in the first semester of 2026, the insurance market in the Republic of Moldova was strongly oriented towards non-life insurance activity, which accounted for 97,2 % of the total gross written premiums by insurance companies (MDL 1 729 million), while the amount of gross written premiums for life insurance was MDL 49.3 million, equivalent to 2,8 % of the total volume of gross premiums written.
The total volume of gross written premiums for non-life insurance activity increased by MDL 184.4 million or 11,9 % compared to the first half of 2025. The gross written premiums for life insurance during the period considered increased by MDL 0.9 million or 1,9 % compared to the gross written premiums during the first semester of the previous year.
On 30 June 2026, the number of policies/contracts in force in the Republic of Moldova was 1 389.3 units, up 31.4 thousand or 2,3 % from the number of contracts in force on 30 June 2025. Of the total number of policies/contracts in force, 98,1 % relate to non-life insurance and 1,9 % to life insurance.
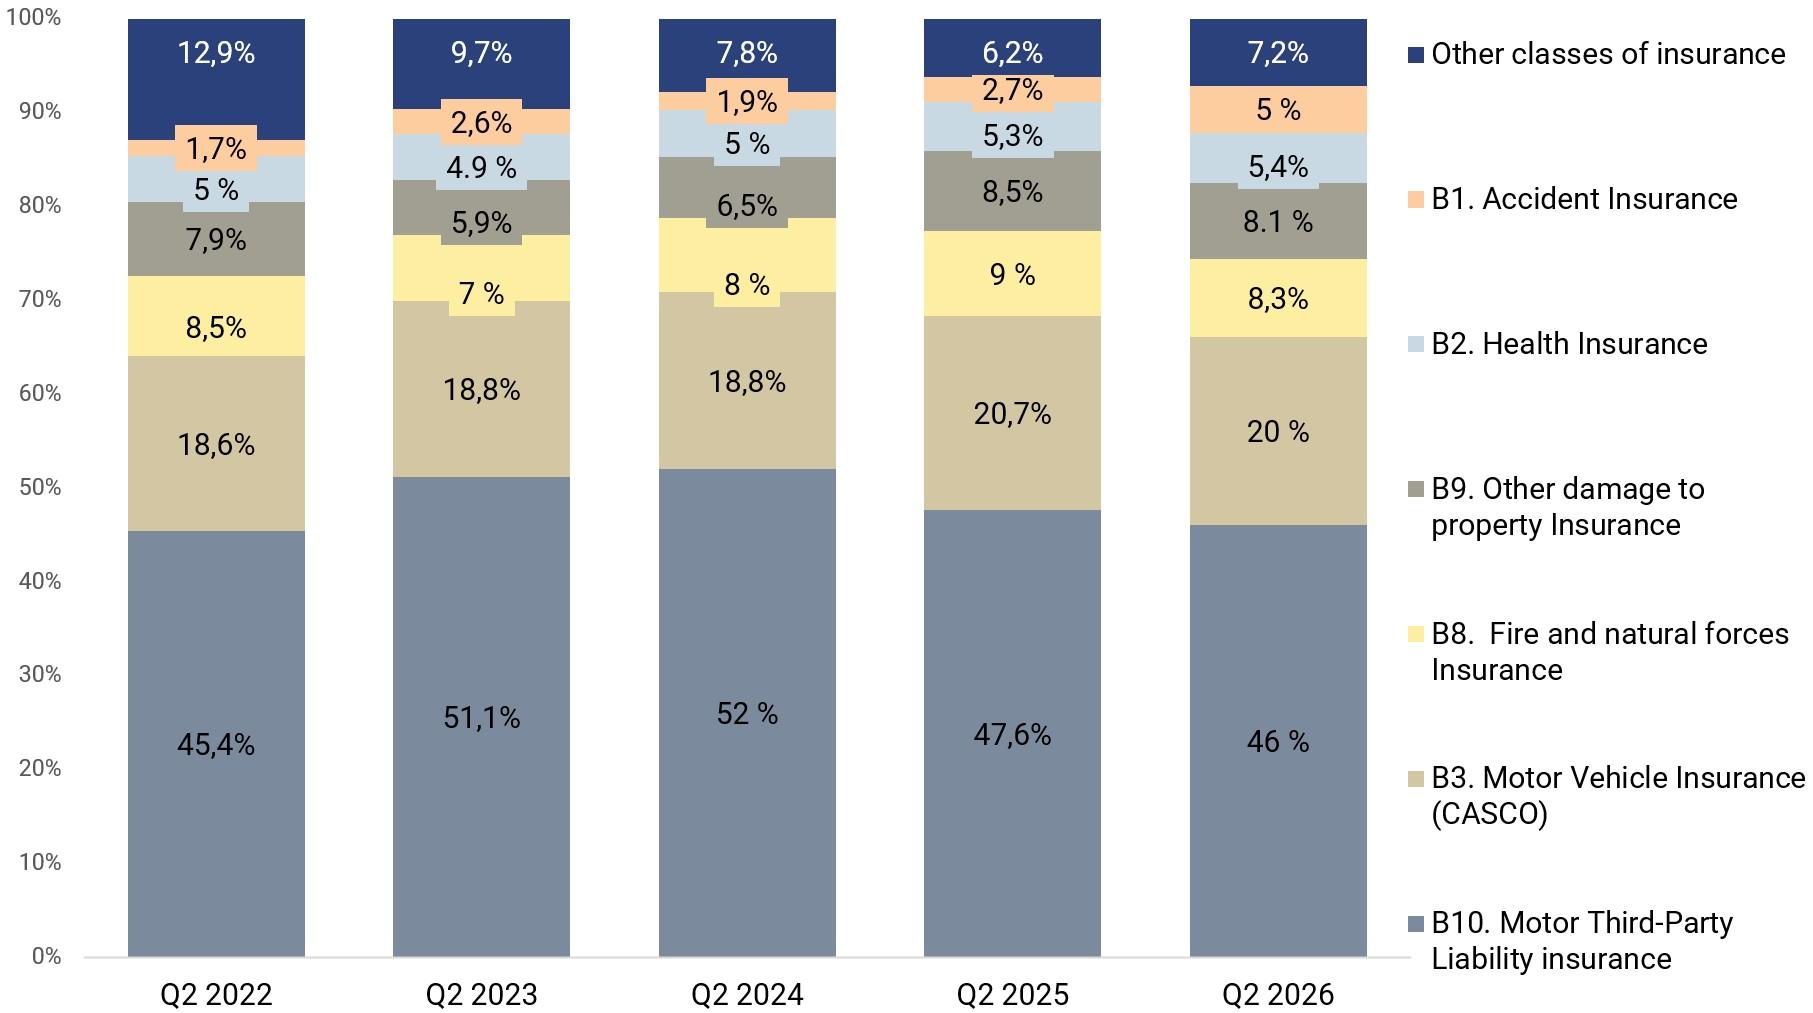
Of the total gross written premiums for non-life insurance, the largest shares were held by Compulsory Motor Third Party Liability Insurance (Internal MTPL, Green Card, TIR Carnet, CMR Carnet) and Motor Vehicle Insurance, other than Railway Rolling Stock (CASCO), thus motor insurance accounting for more than 66 % of the market, followed by Fire and natural forces insurance where 8,3 % of premiums were written, Other damage to property Insurance (mainly agricultural crops insurance) accounting for 8 %, Health Insurance – 5,4 % and Accident Insurance accounting for 5 % of the total volume of underwriting. The other insurance classes account for gross written premiums totalling 7.2 % of total gross written premiums.
Chart No 2 Trends in the structure of gross written premiums by classes of non-life insurance
Gross written premiums for compulsory motor insurance (Internal MTPL, Green Card) comprise 44,3 % of total gross written premiums or MDL 787.5 million, an increase of MDL 60 million or 8,2 % compared with the previous year.
The gross written premiums for internal MTPL insurance in the first half of 2026 amounted to MDL 571.6 million, MDL 51.4 million or 9,9 % more compared to the first half of 2025. The amount of gross written premiums for external motor insurance (Green Card) on 30 June 2026 amounted to MDL 215.9 million, MDL 8.6 million or 4,2 % more than in the similar period of the previous year.
The average premium for internal MTPL insurance in the reference period was MDL 1 344,7/unit, MDL 97/unit or 7,8 % more than in the same period of the previous year. For Green Card insurance, the average premium was MDL 1 125,9/unit, which was MDL 134,9/unit or 13,6 % higher than in the first half of 2025.
In the first half of 2026, insurance companies reported gross claims paid, cumulated for the two categories of insurance, amounting to MDL 776.5 million, MDL 120.2 million or 18,3 % higher than claims paid during the similar period of the previous year, of which:
• MDL 736.6 million or 94.9 % represented compensation for non-life insurance contracts, an increase of MDL 109.4 million or 17.4 % compared with the similar period in the previous year.
• MDL 39.8 million or 5,1 % were the amounts paid for life insurance indemnities (including annuities and payments for contracts that have reached maturity), showing an increase of MDL 10.8 million or 37,4 % compared to the first half of 2025.
For non-life insurance, insurance claims paid by companies have been on an upward trend over the last five years. As regards the classes of insurance, the largest shares of the total gross non-life insurance claims are held by Motor Third Party Liability Insurance and Motor Vehicle Insurance, other than Railway Rolling Stock (CASCO), which comprise more than 86,9 % of the claims paid over the period considered.
Chart No 3 Trends in the structure of claims by classes of non-life insurance
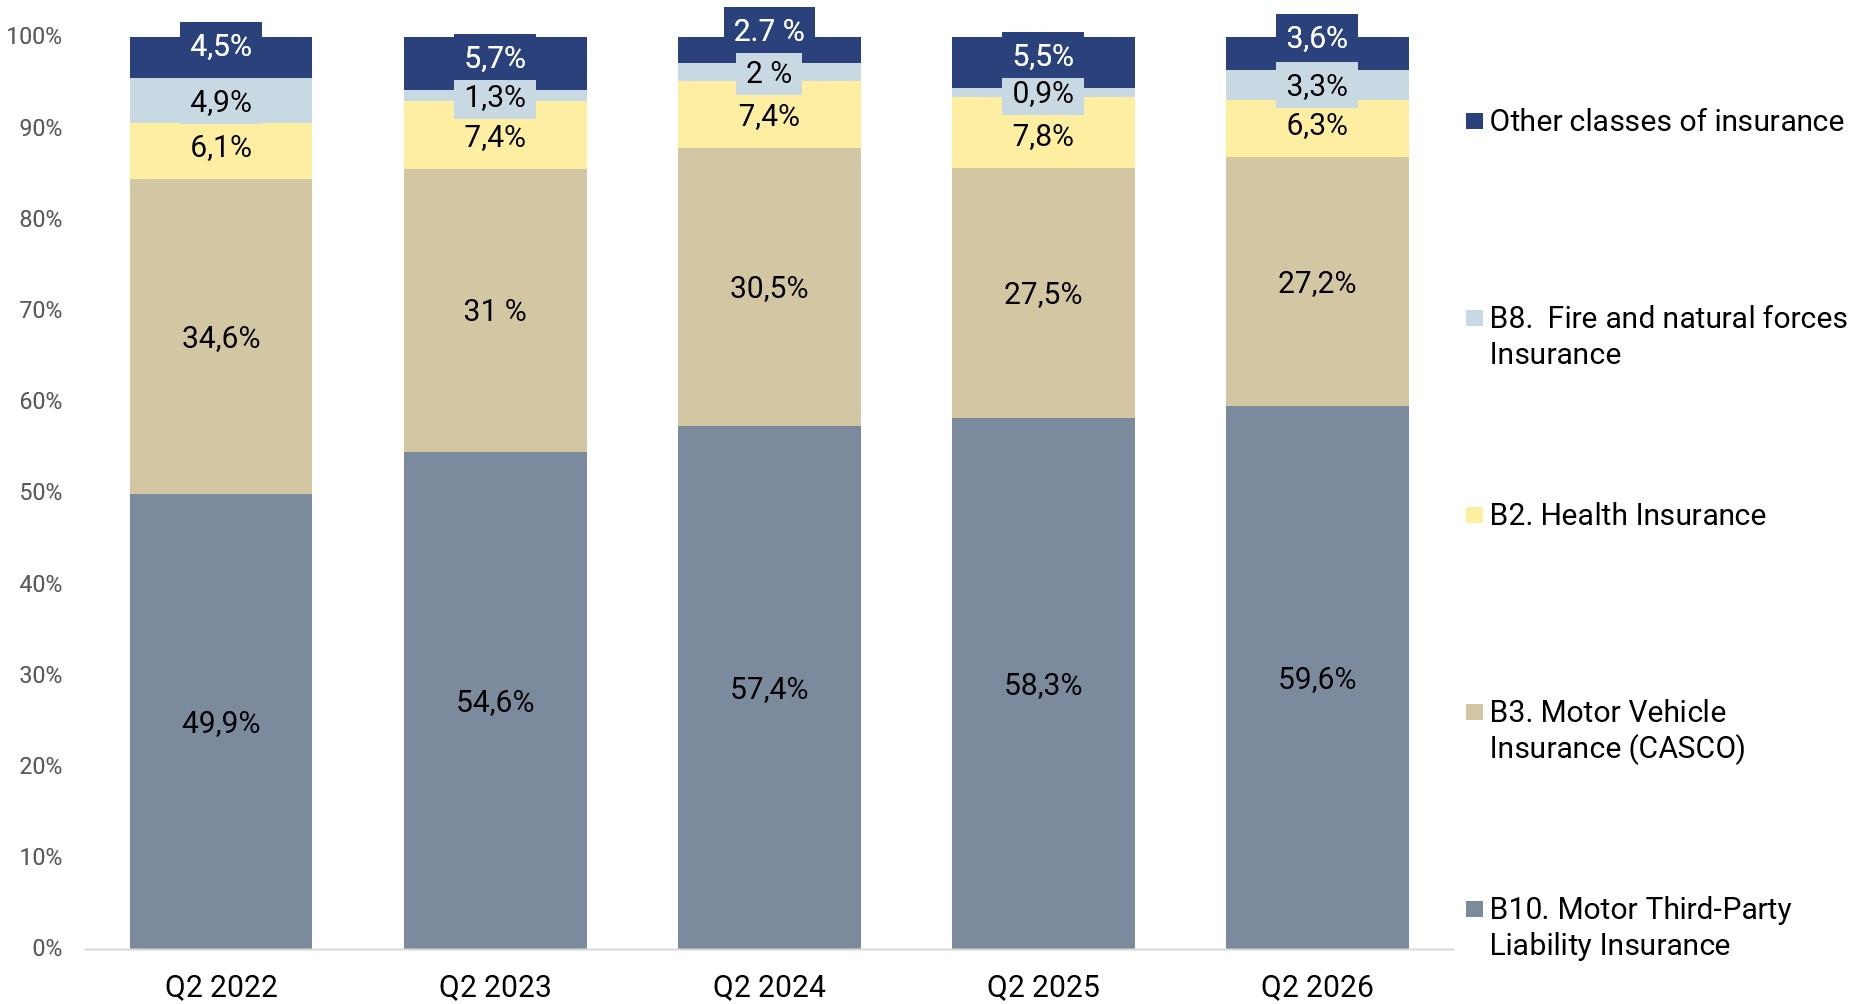
Of the total amount of claims paid, MDL 438.7 million or 56,5 % were claims relating to compulsory insurance (internal MTPL, Green Card), an increase of MDL 73.7 million or 20,2 % compared to the similar period in the previous year. Claims paid for internal MTPL insurance amounted to MDL 344.7 million, MDL 55.1 million or 19 % more than in the first half of 2025. For external MTPL insurance (Green Card), the insurance companies paid claims in the amount of MDL 94 million, MDL 18.6 million or 24,6 % more than in the similar period of the previous year.
The average loss for internal MTPL insurance in the first half of 2026 was MDL 22 559/unit, MDL 1 301,4/unit or 6,1 % more than in the similar period of the previous year. For Green Card insurance, the average claim during the same period was MDL 94 455/unit, MDL 14 040,2/unit or 17,5 % more than on 30 June 2025.
The ratio of claims to premiums (gross amounts) for non-life insurance continued the upward trend, reaching 42,6 % in the reference period, an increase of 2 percentage points compared to the same period of the previous year. It should be noted that, as regards the indicator in question, values ranging from 25.1 % to 62.1 % were recorded in the sector.
The net combined operating ratio (COR), calculated on the basis of aggregated data for all classes of non-life insurance, stood at 97,9 % in the first half of 2026, down 0,7 percentage points from 31 March 2026.
At the level of the entire insurance market, the net technical result for the first half of 2026 was positive, with a net profit of MDL 126.2 million, an increase of MDL 25.7 million or 25,6 % compared to the same period in 2025. All insurance companies reported profits from their operations during the first semester of 2026.
The return on equity (ROE) recorded in the insurance sector in the first half of 2026 was 12.7 %, 8,8 percentage points higher than in 2025. The return on assets (ROA) amounted to 4,1 %, 2,7 percentage points higher than in the previous year.
According to the reports, in the first half of 2026, insurance intermediaries concluded 581.7 thousand insurance contracts (59,2 % of the total contracts concluded on the market – 983.4 thousand contracts), with insurance premiums of MDL 1 055.6 million being intermediated, which represents approximately 59,4 % of the total gross premiums written of MDL 1 778.3 million. As of 30 June 2026, the value of intermediated premiums increased by approximately MDL 5,8 % or MDL 58.2 million compared with the same period in 2025.
The dominant share of intermediated premiums is held by insurance/reinsurance brokers – 73,2 %, insurance agents hold a share of 13,7 %, and bancassurance agents – 13,1 % of all intermediated premiums.
The degree of intermediation at the end of the first half of 2026 was 59.4 %, down 3,2 percentage points compared with the same period the previous year, and by category of insurance it was 58.3 % for non-life insurance and 95.4 % for life insurance.
The commissions calculated by insurance intermediaries constituted MDL 341.2 million, an increase of 2.4 % compared to the similar period in 2025, of which commissions from the intermediation of insurance contracts – MDL 338.8 million or 99.3 % and from assistance and settlement of claims – MDL 2.4 million or 0.7 %.
During the first half of 2026, the Street Victims Protection Fund (hereinafter SVPF) recorded contributions amounting to MDL 5.7 million (1 % of gross premiums written for the internal MTPL), 10 % more compared to the similar period of the previous year, as a result of the increase in the total volume of gross premiums written in respect of internal MTPL insurance.
In the reference period, 109 claims cases were settled from the SVPF, of which 107 cases concern the lack of insurance coverage (82.2 % being accidents caused by vehicles used by natural persons and 17.8 % – by vehicles used by legal persons) and 2 cases – by unidentified users. The amount of compensation paid during the first half of 2026 amounts to MDL 3.8 million, of which MDL 99.4 % relates to damage to property and MDL 0.6 % to personal injuries.
The balance of the SVPF’s cash resources at the end of the management period was MDL 54.1 million, 9,6 % more than at the beginning of the year, of which 95,1 % of the availabilities are placed in government bonds and the remaining 4,9 % are kept in the settlement account.
As of 30 June 2026, contributions amounting to MDL 10.8 million (5 % of the gross premiums written for external MTPL insurance) were calculated for the Compensation Fund , which is 4,4 % more than in the similar period of the previous year, due to the increase in the volume of gross premiums written for external MTPL insurance.
During the reference period, 174 claims were settled from the Compensation Fund, of which 98,3 % relate to damage regularised in the Republic of Moldova (amounts due to persons injured in the Republic of Moldova to compensate for damage caused by holders of “Green Card” insurance certificates issued by foreign insurers) and 1,7 % relate to the reimbursement to foreign counterparties of amounts paid by them as insurance compensation for damage caused by holders of “Green Card” insurance certificates, members of NBMIM. The amount of compensation paid amounted to MDL 6.2 million, of which MDL 99.4 % relates to damage to property and MDL 0.6 % to personal injuries. The amount of compensation paid during the reporting period decreased by 7,6 % compared to the similar period of the previous year, when compensation of MDL 6.7 million was paid.
On 30 June 2026, the Compensation Fund recorded cash in the amount of MDL 193.1 million, 6 % more than at the beginning of the year, of which 56,4 % of the availabilities are placed in bank deposits, 42 % in government bonds and 1,6 % in settlement accounts.
During the first half of 2026, the National Bank of Moldova continued the work on drafting and updating secondary normative acts for the implementation of Law No 92/2022 on the business of insurance and reinsurance.
At the same time, the National Bank of Moldova continued work on strengthening the regulatory framework for insurance business and aligning national legislation with European Union standards.
In this regard, the draft Law on the business of insurance and reinsurance, which provides for the transposition of the relevant European legislation, namely Directive 2009/138/EC of 25 November 2009 on the taking-up and pursuit of the business of Insurance and Reinsurance (Solvency II), and the draft Law on compulsory motor third party liability insurance for damages caused to third parties by vehicle accidents, which transposes into national law the provisions of Directive 2009/103/EC relating to insurance against civil liability in respect of the use of motor vehicles, and the enforcement of the obligation to insure against such liability, were submitted to anti-corruption and legal expertise, in accordance with the procedure laid down by the legislative framework.


