Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!


Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!
Cele mai populare rapoarte statistice:
Banca Naţională şi membrii organelor de conducere ale acesteia sunt independenţi în exercitarea atribuţiilor stabilite de lege şi nu pot solicita şi nici accepta instrucţiuni de la autorităţile publice sau de la orice altă autoritate.
Banca Naţională informează publicul despre evoluția inflației anuale, strategia de politică monetară,rezultatele analizei macroeconomice, evoluţiei pieţei financiare şi informaţia statistică, inclusiv privind masa monetară, acordarea creditelor, balanţa de plăţi şi situaţia pieţei valutare.
Pentru asigurarea şi menţinerea stabilităţii preţurilor pe termen mediu, Banca Naţională a Moldovei menţine inflaţia (măsurată prin indicele preţurilor de consum) la nivelul de 5.0 la sută anual cu o posibilă abatere de ± 1.5 puncte procentuale, fiind considerat nivelul optim pentru creşterea şi dezvoltarea economică a Republicii Moldova pe termen mediu.
Stabilitatea financiară se realizează prin consolidarea rezilienței sistemului financiar, limitarea efectului de contagiune și diminuarea acumulării de riscuri sistemice, contribuind, astfel, la sustenabilitatea sectorului financiar și creșterea economică.
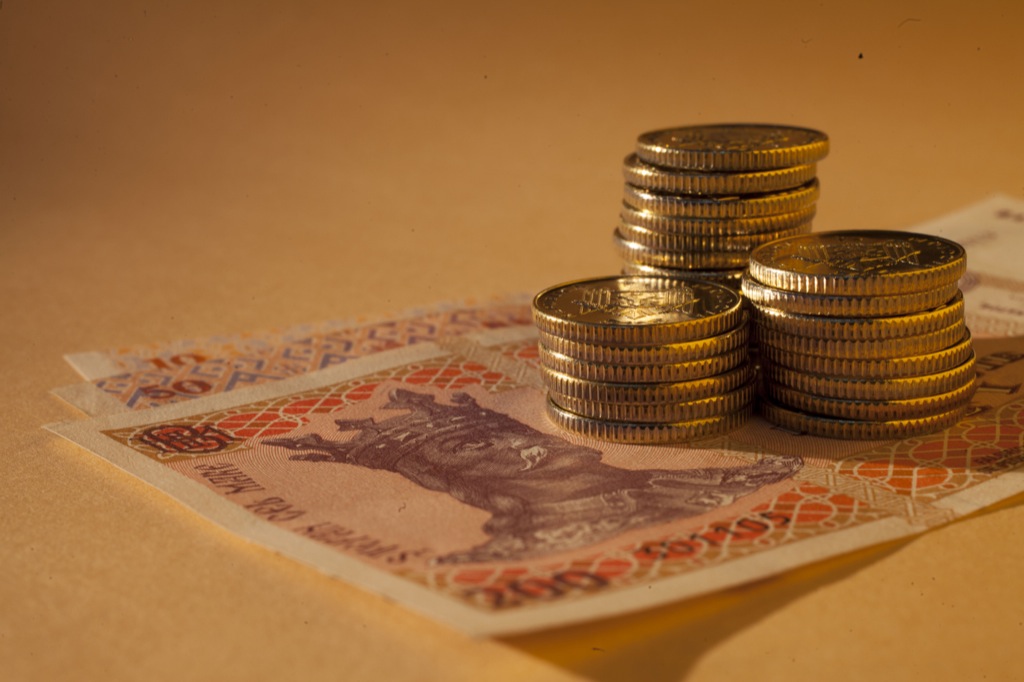
Banca Naţională a Moldovei, are dreptul exclusiv de a emite pe teritoriul Republicii Moldova bancnote şi monede metalice ca mijloc de plată. BNM pune în circulaţie bancnote şi monede metalice, prin intermediul sistemului bancar.
Banca Naţională este unica instituţie care efectuează licenţierea, supravegherea şi reglementarea activităţii instituţiilor financiare.
Banca Națională supraveghează sistemul de plăţi în Republica Moldova şi promovează funcţionarea stabilă şi eficientă a sistemului automatizat de plăţi interbancare.
Banca Naţională este o persoană juridică publică autonomă şi este responsabilă faţă de Parlament.
BNM publică statistici privind masa monetară, sectorul bancar, balanța de plăți, situația pieței valutare, etc. pentru a asigura transparența în procesul de elaborare și adoptare a deciziilor BNM, a asigura continuitatea în comunicare și predictibilitatea BNM pe piață, pentru sporirea credibilității BNM în calitate de bancă centrală dar și pe piața financiar-bancară din Republica Moldova.
Domestic and foreign currency loans accounted for 67.3% and – 32.7%, respectively. (Chart 1 below).
Domestic currency loans totalled MDL 1,923.8 million (+7.2% compared to the previous month and +32.4% compared to March 2018 (Chart 1 below)).
Foreign currency loans recalculated in MDL, totalled MDL 935.2 million (+31.2% compared to the previous month and +22.4% compared to March 2018 (Chart 1 below)).
Chart 1
Dynamics of new loans, million MDL (upper chart) and the annual growth rate of new loans extended by banks, % (lower chart).

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
It should be mentioned that, in terms of maturity, loans with maturity ranging from 2 to 5 years recorded the highest demand (45.5% of total loans extended), out of which the largest share of 31.0% was held by legal entities (Chart2).
Chart 2
New loans extended, by maturity terms and shares held, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Domestic currency loans were mainly represented by loans extended to individuals (47.8%) as well as loans extended to non-financial commercial companies holding a share of 45.8% (47.5% belong to trade companies) (Chart 3).
Foreign currency loans were mainly requested by non-financial commercial companies (91.0%), trade companies having the biggest share (47.0%).
Chart 3
Domestic currency loans broken down by business sectors, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Chart 4
Weighted average interest rates on new loans, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Average interest rate on domestic currency loans decreased by 0.13 percentage points compared to previous month, recording levels of 7.54% (individuals’ loans) and 8.76% (legal entities loans) (Chart 4).
Average interest rate on foreign currency loans decreased by 0.19 percentage points compared to February 2019, recording levels of 5.62% (individuals’ loans) and 4.25% (legal entities loans).
Year-on-year average interest rates on loans recorded a total decrease of 1.18 percentage points (domestic currency loans) and 0.42 percentage points (foreign currency loans).
Chart 5
Average interest rates on domestic currency loans, by maturity terms, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Domestic currency loans with maturity ranging from 2 to 5 years recorded the highest demand in the reporting month and were extended at an average interest rate of 8.09% (8.69% on legal entities loans, 7.47% on individual’s loans) (Chart 5).
It should be mentioned that the highest average interest rate on loans extended in domestic currency was registered on loans with maturity of up to 1 month (10.73%), 11.24% - on individuals’ loans and 10.58% - on legal entities loans. (Chart 5)
Chart 6
Average interest rates on foreign currency loans, by maturity terms, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Foreign currency loans with maturity ranging between 2 and 5 years, recorded the highest demand and were extended at an average interest rate of 4.27% (individuals’ loans – at 5.58%, legal entities loans – at 4.27%) (Chart 6)
Chart 7
Dynamics of new term deposits (upper chart) compared to statistics of the previous month (lower chart), million MDL

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Domestic currency deposits totalled MDL 1,464.6 million (-13.9% compared to the previous month and -6.2% compared to March 2018).
Foreign currency deposits, recalculated in MDL, totalled MDL 904.0 million (+14.4% compared to the previous month and +11.3% compared to March 2018).
Domestic currency deposits accounted for a share of 61.8%, while foreign currency deposits – 38.2% of total deposits.
Chart 8
Total deposits by maturity terms and shares held, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
In March 2019, deposits were mainly represented by individuals’ deposits – 86.3% (of which 49.7% - domestic currency deposits and 36.6% - foreign currency deposits).
In terms of maturity, the highest demand was recorded for deposits placed for a period ranging from 6 to 12 months (38.5% of total term deposits). It is worth mentioning that the largest share was held by individuals’ deposits (33.4% of total deposits placed).
Chart 9
Weighted average interest rates on new deposits, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Average interest rate on new term deposits in domestic currency increased by 0.01 percentage points compared to the previous month. Individuals’ deposits were placed at an average interest rate of 4.59%, while legal entities deposits – at 3.38%.
Average interest rate on new term deposits in foreign currency decreased by 0.08 percentage points compared to February 2019. Individuals’ deposits were placed at an average interest rate of 0.85%, while legal entities deposits – at 1.14%.
Year-on-year, average deposit interest rates decreased. Thus, average interest rate on domestic currency deposits decreased by 0.30 percentage points (individuals’ deposits - by 0.30 percentage points, legal entities deposits - by 0.62 percentage points). Average interest rate on foreign currency deposits decreased by 0.21 percentage points (individuals’ deposits decreased by 0.13 percentage points and legal entities deposits by 0.58 percentage points).
Chart 10
Average interest rates on domestic currency deposits, by maturity terms, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Domestic currency deposits with maturity ranging from 6 to 12 months, which recorded the highest demand in the reporting period, were placed at an average interest rate of 4.69% (individuals’ deposits – 4.95%, legal entities deposits – 3.36%) (Chart 10) whereas the foreign currency were placed at an average interest rate of 0.96% (individuals’ deposits – 0.95%, legal entities deposits– 1.09%) (Chart 11).
The highest average interest rate on domestic currency deposits was recorded for individuals’ deposits with maturity ranging from 1 to 2 years (5.48%) and over 5 years (5.54%), and legal entities deposits with maturity from 1 to 2 years (4.10%) (Chart 10)
Chart 11
Average interest rates on foreign currency deposits, by maturity terms, %

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
The highest average interest rate on foreign currency deposits was recorded for individuals’ deposits with maturity ranging over 5 years (1.31%), as well as legal entities deposits (1.50%).
Chart 12
Bank interest margin, annual percentage points

Source: The NBM’s report on average rates on new loans and deposits recorded in the banking system for March 2019.
Bank interest margin on domestic currency operations decreased by 0.14 percentage points compared to the previous month and by 0.88 percentage points compared to March 2018.
Bank interest margin on foreign currency operations decreased by 0.11 percentage points compared to the previous month and by 0.21 percentage points compared to March 2018.
______________________________________________
1. The data are presented according to the Guidelines on Preparation and Presentation of Reports on Interest Rates applied by banks in the Republic of Moldova, approved by the Decision of the Executive Board of the NBM no. 331 of 01 December 2016, which were published in the Official Monitor of the Republic of Moldova no.441-451 of 16 December 2016, with subsequent amendments and completions.
2. Including economically active individuals’.


