Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!


Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!
Cele mai populare rapoarte statistice:
Banca Naţională şi membrii organelor de conducere ale acesteia sunt independenţi în exercitarea atribuţiilor stabilite de lege şi nu pot solicita şi nici accepta instrucţiuni de la autorităţile publice sau de la orice altă autoritate.
Banca Naţională informează publicul despre evoluția inflației anuale, strategia de politică monetară,rezultatele analizei macroeconomice, evoluţiei pieţei financiare şi informaţia statistică, inclusiv privind masa monetară, acordarea creditelor, balanţa de plăţi şi situaţia pieţei valutare.
Pentru asigurarea şi menţinerea stabilităţii preţurilor pe termen mediu, Banca Naţională a Moldovei menţine inflaţia (măsurată prin indicele preţurilor de consum) la nivelul de 5.0 la sută anual cu o posibilă abatere de ± 1.5 puncte procentuale, fiind considerat nivelul optim pentru creşterea şi dezvoltarea economică a Republicii Moldova pe termen mediu.
Stabilitatea financiară se realizează prin consolidarea rezilienței sistemului financiar, limitarea efectului de contagiune și diminuarea acumulării de riscuri sistemice, contribuind, astfel, la sustenabilitatea sectorului financiar și creșterea economică.
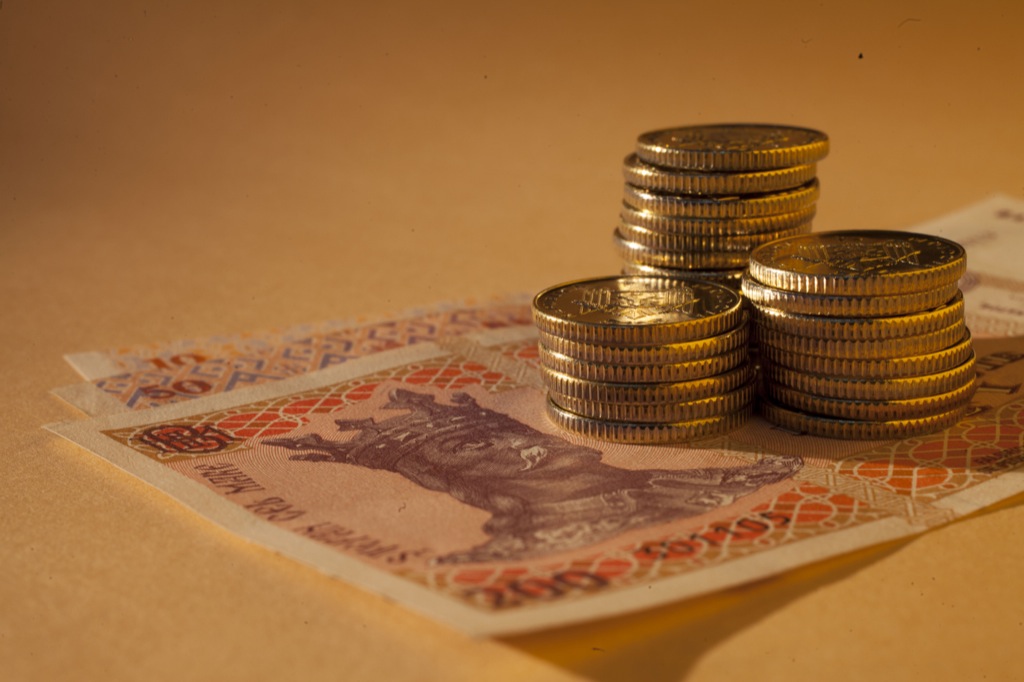
Banca Naţională a Moldovei, are dreptul exclusiv de a emite pe teritoriul Republicii Moldova bancnote şi monede metalice ca mijloc de plată. BNM pune în circulaţie bancnote şi monede metalice, prin intermediul sistemului bancar.
Banca Naţională este unica instituţie care efectuează licenţierea, supravegherea şi reglementarea activităţii instituţiilor financiare.
Banca Națională supraveghează sistemul de plăţi în Republica Moldova şi promovează funcţionarea stabilă şi eficientă a sistemului automatizat de plăţi interbancare.
Banca Naţională este o persoană juridică publică autonomă şi este responsabilă faţă de Parlament.
BNM publică statistici privind masa monetară, sectorul bancar, balanța de plăți, situația pieței valutare, etc. pentru a asigura transparența în procesul de elaborare și adoptare a deciziilor BNM, a asigura continuitatea în comunicare și predictibilitatea BNM pe piață, pentru sporirea credibilității BNM în calitate de bancă centrală dar și pe piața financiar-bancară din Republica Moldova.
The financial situation of the banking sector, according to data submitted by banks, is characterised by growth in assets, loans, own funds, own funds ratio, deposits of individuals, and deposits of legal entities. The profit for the year compared to the same period of the previous year increased, mainly, due to higher interest and non-interest income. Interest income increased, mainly, due to income from investments in debt securities (G-Sec, NBC) and income from lending activity.
At the same time, there was a decrease in the absolute value of expired loans, non-performing loans, therefore, the quality indicators of the loan portfolio improved.
As of December 31, 2023, 11 banks licensed by the National Bank of Moldova were active in the Republic of Moldova.
As of December 31, 2023, the situation in the banking sector, reflected by the reports submitted by banks, registered the following trends:
Assets and liabilities
Total assets amounted to MDL 153 940,5 million, increasing by 17,2% (MDL 22 572,3 million) over 2023.
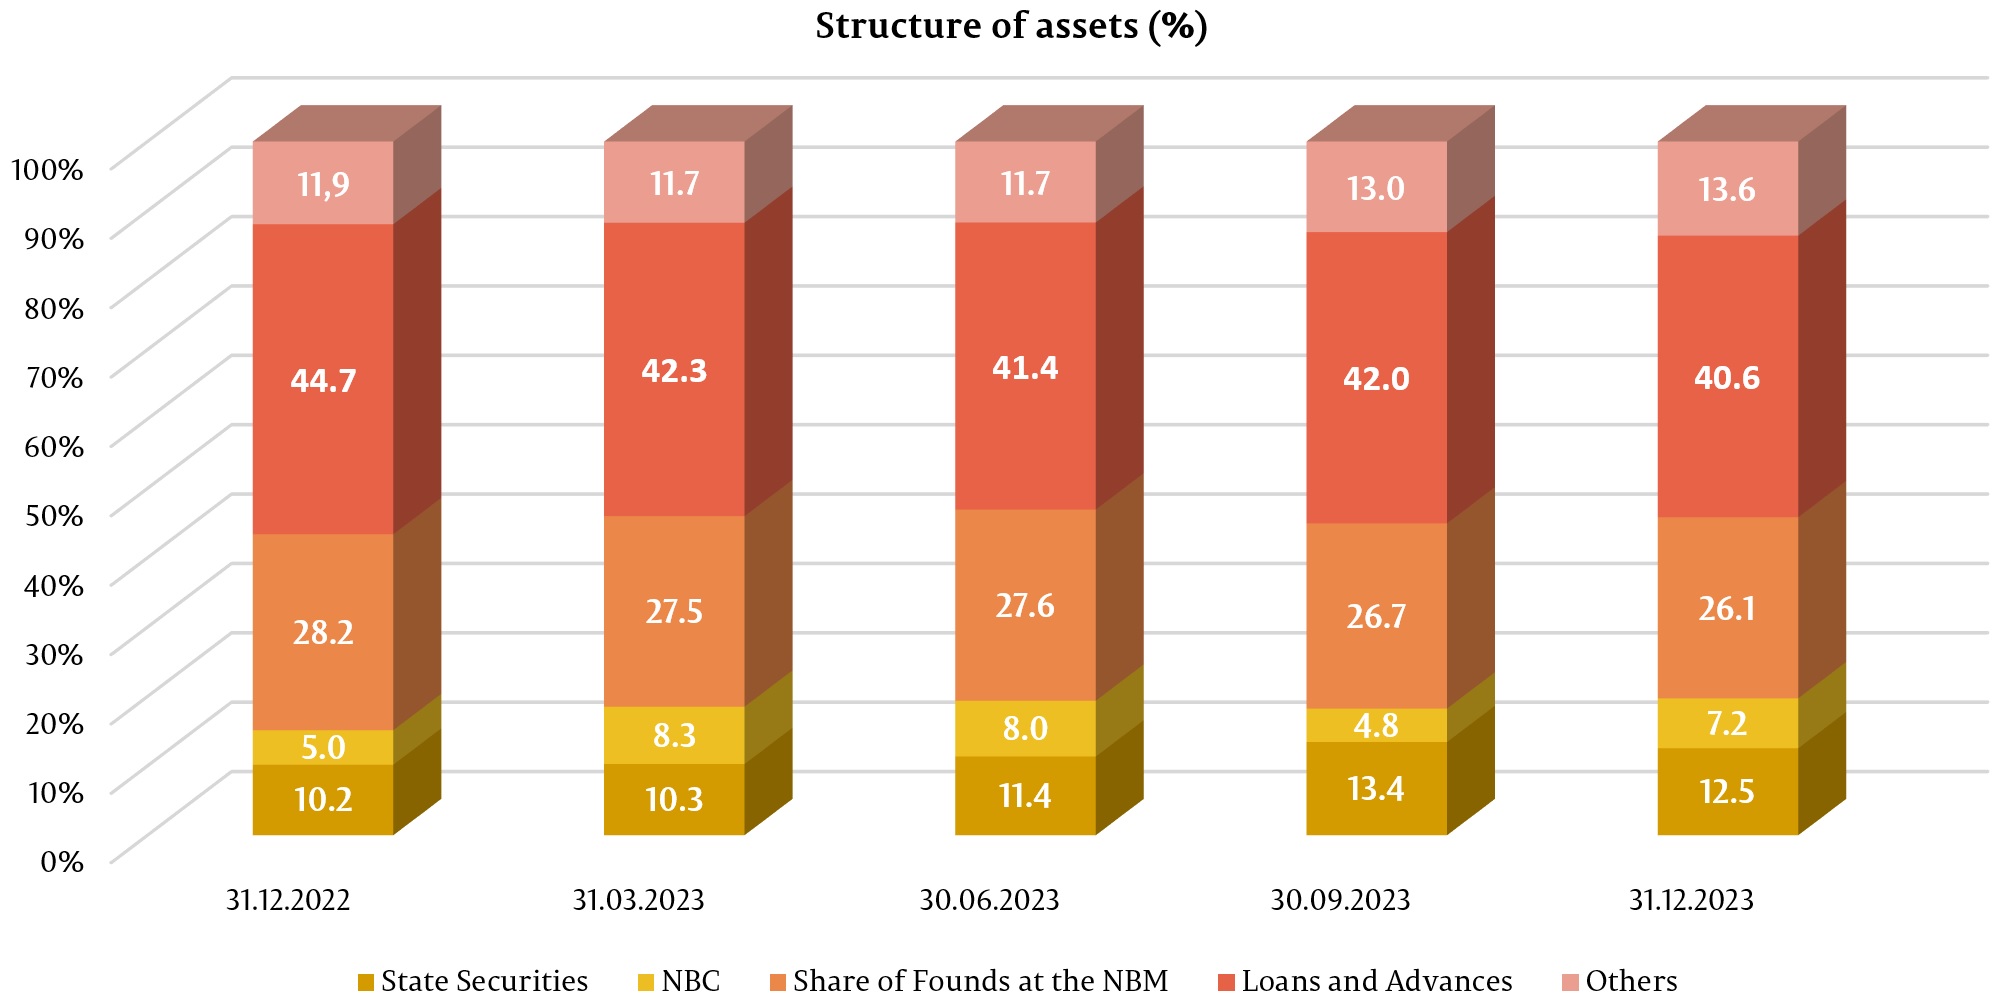
The largest share in total assets went to “Loans and advances at amortized cost” which amounted to 40,6% (MDL 62 487,1 million), decreasing by 4,1 percentage points (pp) compared to the end of the previous year.
The share of funds at the NBM was 26,1% (MDL 40 181,4 million), decreasing by 2,1 pp, and the share of banks' investments in state securities and National Bank certificates accounted for 19,7% (MDL 30 392,3 million), increasing by 4,5 pp. The rest of the assets, which account for 13,6% (MDL 20 879,7 million), are kept by banks in other banks, in cash, tangible fixed assets, intangible fixed assets, etc. Their share increased by 1,7 pp compared to the end of 2022.
The gross (prudential) balance of loans accounted for 41,5% of total assets, or MDL 63 895,5 million, increasing during the period under review by 3,7% (MDL 2 268,3 million).
The largest increase was recorded in loans granted to consumers – by MDL 1 190,4 million (11,9%) up to MDL 11 199,9 million; loans granted to the purchase/construction of real estate – by MDL 989,1 million (8,1%) up to MDL 13 282,3 million; loans granted to trade – by MDL 358,4 million (2,6%) up to MDL 14 238,7 million, loans granted to the non-bank financial institutions – by MDL 288,3 million (11,7%) up to MDL 2 757,6 million.
At the same time, the largest degrease during 2023 was recorded to loans granted to food industry – by MDL 248,1 million (5,6%) up to MDL 4 151,7 million, to loans granted to construction – by MDL 230,8 million (16,3%) up to MDL 1 186,5 million, to other loans granted – by MDL 181,0 million (7,3%) up to MDL 2 290,2 million and loans granted to energy industry – by MDL 178,2 million (19,2%) up to MDL 749,1 million.
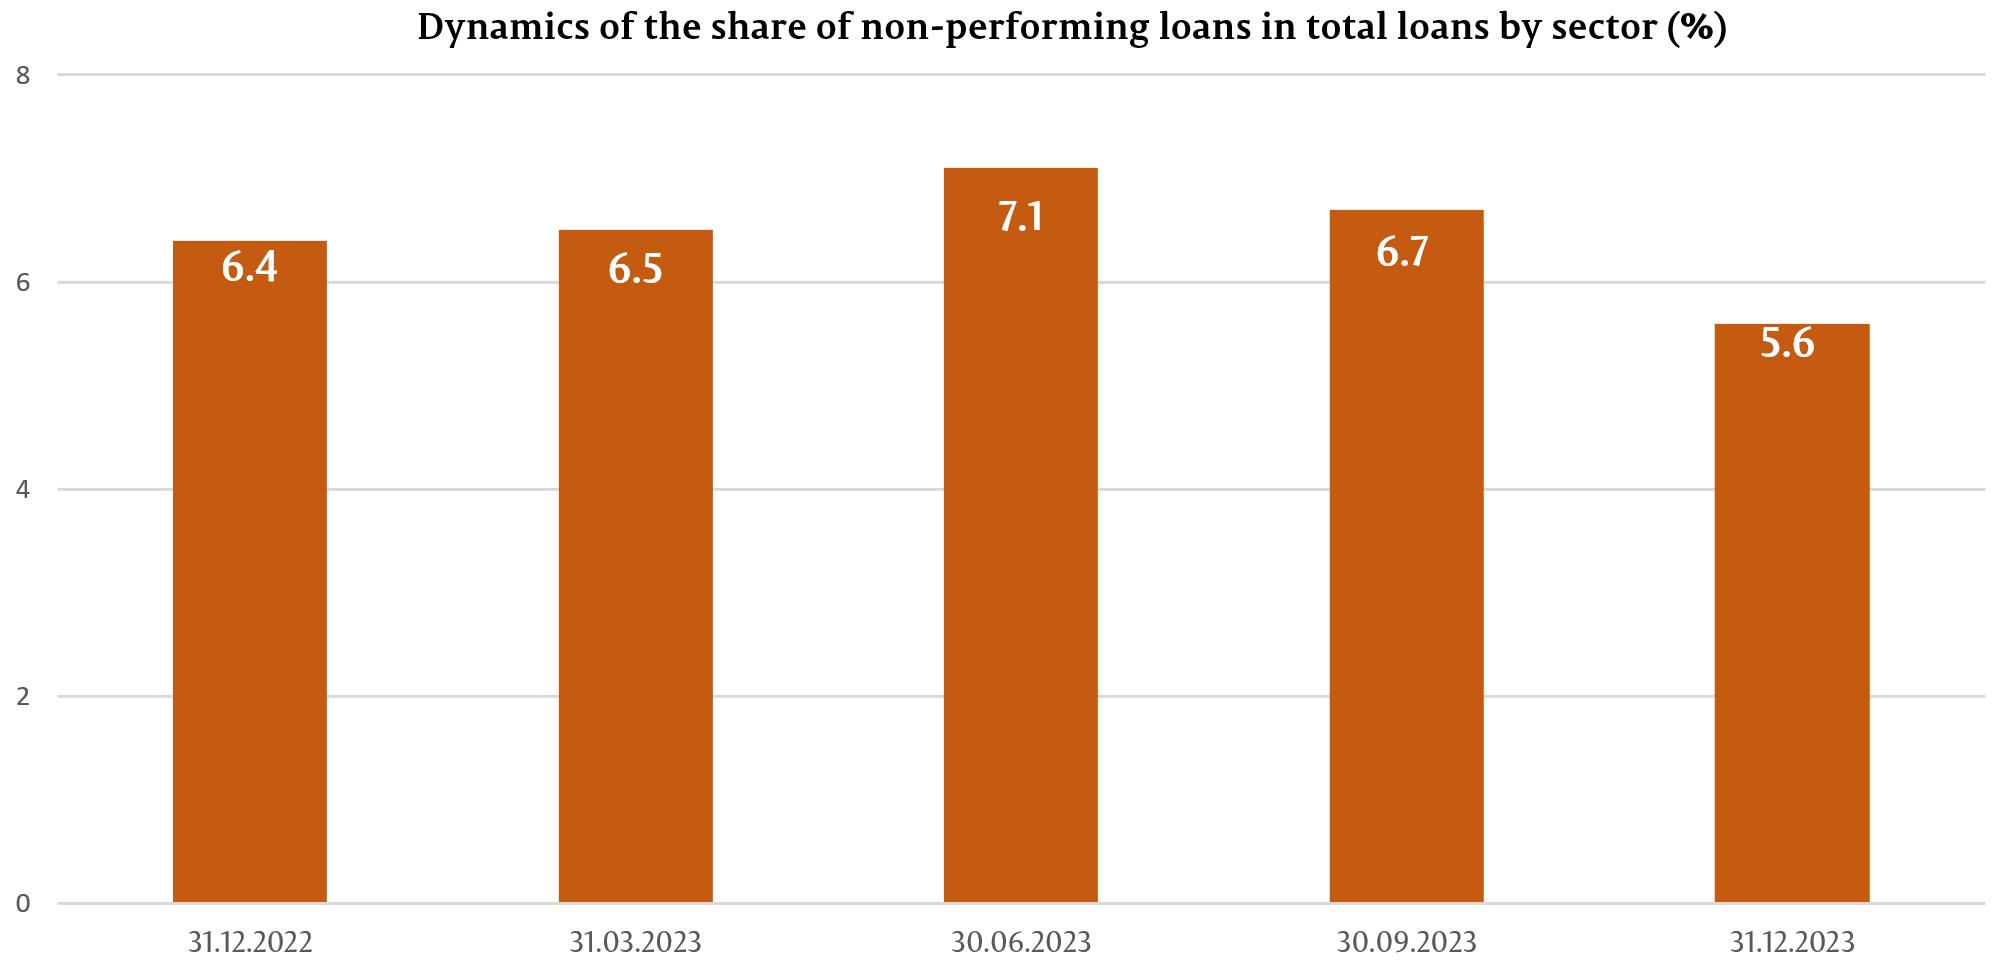
During the reference period, the share of non-performing loans (substandard, doubtful, and compromised) in total loans decreased by 0,9 pp, accounting for 5,6% on 31.12.2023, with the indicator ranging from 2,4% to 7,2%, depending on the bank.
At the same time, non-performing loans in absolute value decreased by 10,7% (MDL 423,2 million) to MDL 3 547,2 million.
During the period under review, the share of expired loans increased by 1,6% (MDL 32,2 million) to MDL 2 038,9 million. The share of expired loans in total loans was 3,2%, decreasing by 0,1 pp compared to 31.12.2022, ranging from 1,6% to 5,4%, depending on the bank.
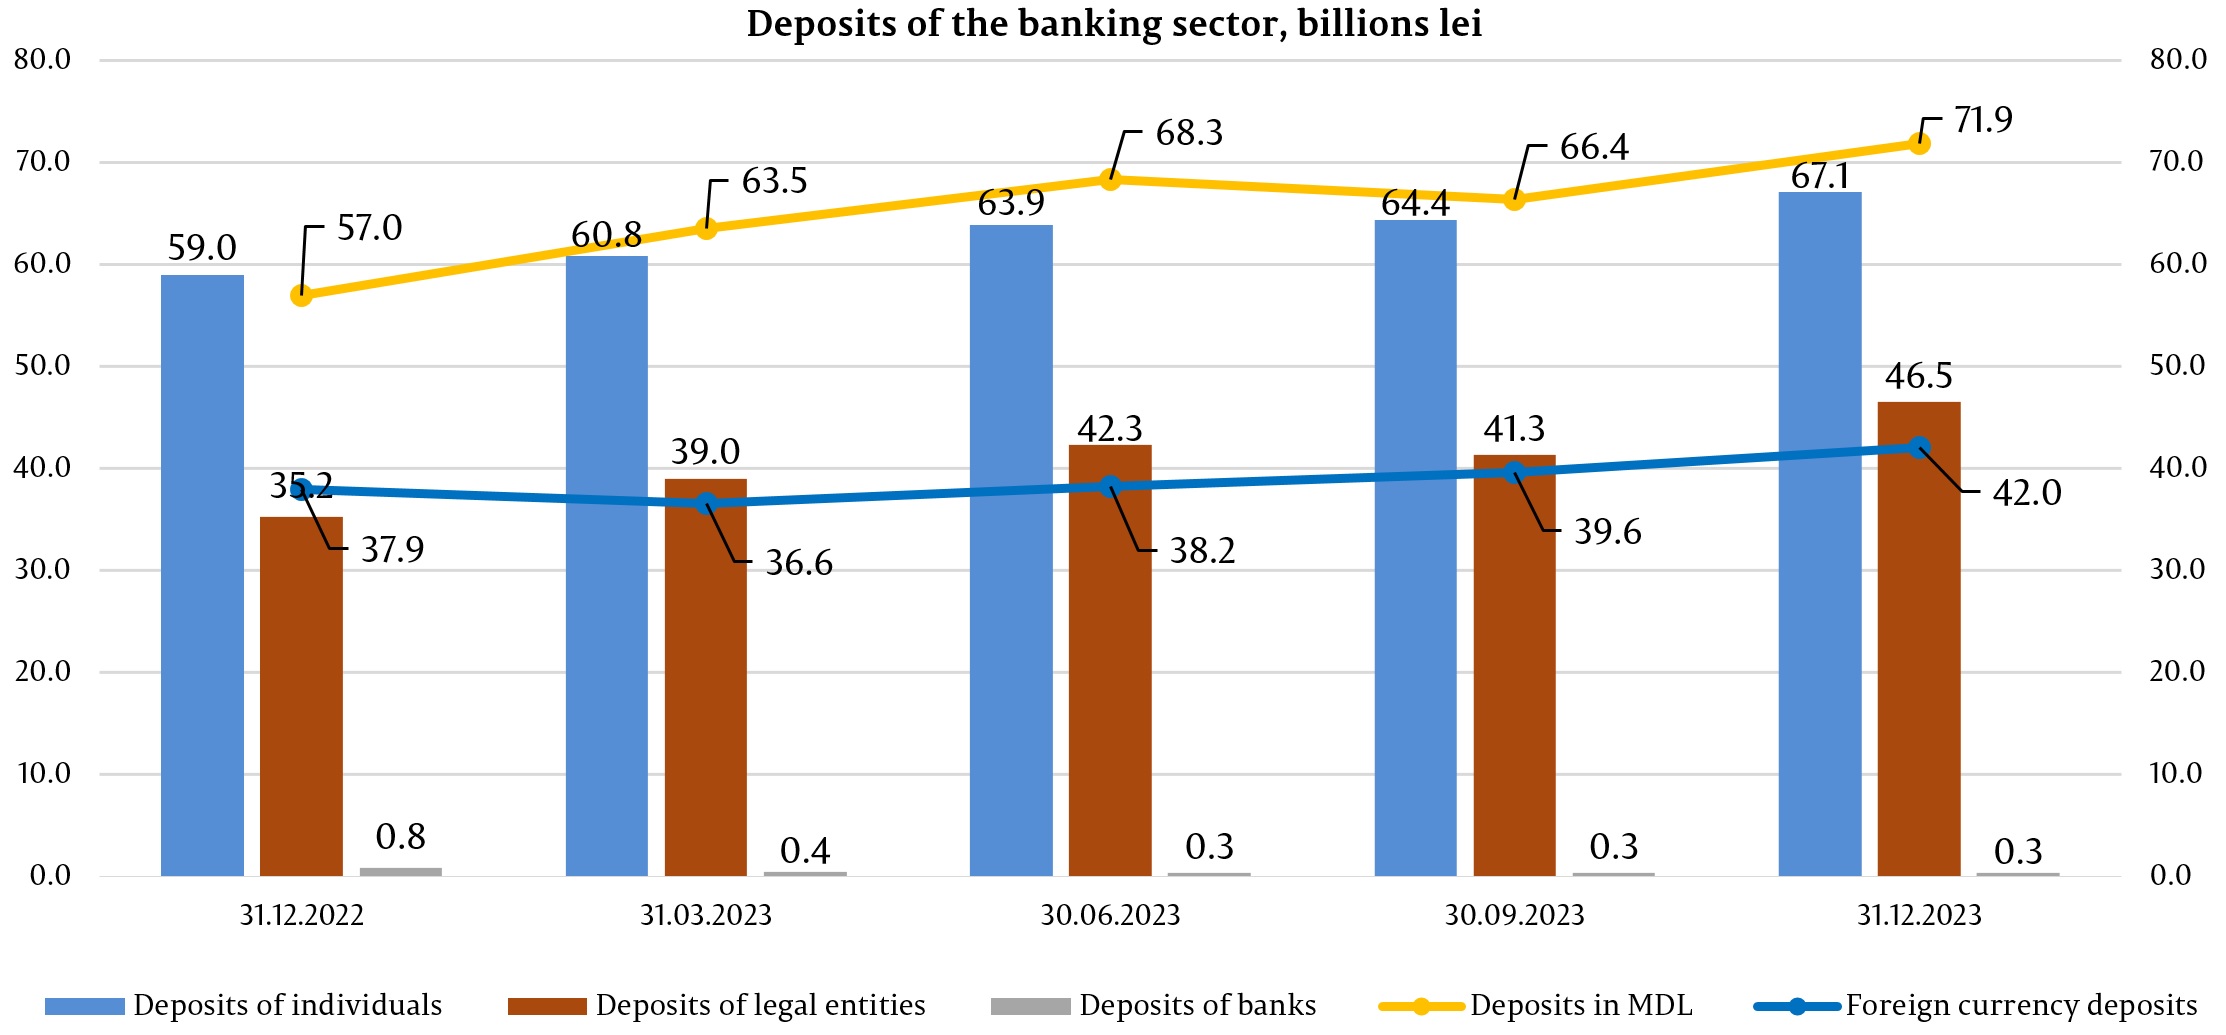
At the same time, during the reference period the total balance of deposits increased by MDL 18 892,8 million, or by 19,9% amounting to MDL 113 861,3 million (deposits of individuals accounted for 58,9% of total deposits, deposits of legal entities – 40,8%, and deposits of banks – 0,2%), as a result of the increase in the balance of deposits of legal entities by MDL 11 321,7 million (32,2%) up to MDL 46 505,5 million, and deposits of individuals by MDL 8 070,9 million (13,7%) up to 67 088,6 million. At the same time, the balance of bank deposits decreased by MDL 499,8 million (65,2%) up to MDL 267,2 million.
In total deposits, 63,1% went to deposits in MDL, their balance increasing by MDL 14 881,7 million (26,1%) compared to the end of the previous year and amounted to MDL 71 902,1 million on 31.12.2023. Foreign currency deposits accounted for 36,9% of total deposits, their balance increased during the reference period by MDL 4 011,1 million (10,6%), making up MDL 41 959,2 million (attracting foreign currency deposits - equivalent to MDL 6 223,4 million, negative revaluation of foreign currency deposits – MDL (-2 360,6) million).
Revenues and profitability
As of December 31, 2023, the profit in the banking system amounted to MDL 4 123,4 million, increasing by MDL 459,1 million (12,5%) compared to similar period of the previous year.
The increase in profit was due to the increase in interest income by MDL 1 829,6 million (19,0%), income from fees and commissions by MDL 302,8 million (10,1%) and from exchange rate differences by MDL 175,5 million (10,2%). At the same time, non-interest expenses (expenses related to fees and commissions, administrative expenses, provisions, impairment of financial and non-financial assets, etc.) decreased by MDL 183,2 million (2,2%), while interest expenditure increased by MDL 1 977,0 (78,2%).
Total revenues amounted to MDL 16 803,8 million, increasing compared to the similar period of the previous year by MDL 2 252,9 million (15,5%), of which interest income amounted to MDL 11 463,7 million (68,2% of total revenues), and non-interest income – MDL 5 340,1 million (31,8% of total revenues).
At the same time, total expenditure amounted to MDL 12 680,4 million, increasing compared to the similar period of the previous year by MDL 1 793,8 million (16,5%), of which interest expenditure was MDL 4 506,4 million (35,5% of total expenditure), and non-interest expenditure – MDL 8 174,0 million (64,5% of total expenditure).
As of December 31, 2023, return on assets accounted for 2,8%, decreasing insignificantly by 0,1 pp compared to the end of the previous year and return on capital accounted for 16,3%, decreasing by 0,7 pp compared to the end of the previous year.
Compliance with prudential requirements
Over 2023, banks continued to maintain liquidity indicators at a high level, above regulated limits.
Thus, the value of the long-term liquidity indicator (liquidity principle I) was 0,69 (limit ≤1), ranging from 0,31 to 0,83, depending on the bank, increasing by 0,02 as compared to the end of 2022.
Liquidity Principle III, which is the ratio of adjusted effective liquidity to required liquidity on each maturity band and which should not be less than 1 on each maturity band, has also been complied with by all banks, ranging from 1.48 on the maturity band up to one month inclusive up to 124,33 on the maturity band between one month and three months inclusive.
The liquidity coverage ratio by sector amounted to 282,3% (limit ≥ 100% - starting with 1 January 2023), ranging from 195,5% to 661,6%, increasing by 46,8 pp compared to the end of 2022.
According to the reports submitted by banks as of December 31, 2023, the total own funds ratio in the banking sector recorded a value of 30,0%, increasing by 0,7 pp compared to the end of the previous year, ranging from 23,6% and 57,4%. All banks met the indicator "Total own funds ratio" (≥10%).
All banks also complied with the "Total Own Funds Ratio" indicator requirement, considering capital buffers.
As of December 31, 2023, total own funds amounted to MDL 20 947,3 million and registered an increase of 14,1% (MDL 2 589,9 million). The increase in own funds was mainly determined by the reflection by some banks of eligible profits after the general meetings of shareholders and after obtaining the permission of the NBM to include the profits earned in own funds. At the same time, there was an increase in the positive difference between allowances for losses on assets and contingent liabilities and the size of allowances for impairment losses on assets and loss provisions.
As of December 31, 2023, the banks complied with the prudential indicators regarding large exposures and exposures to their affiliates, with the exception of one bank, which exceeded the limit of 30% on the aggregate amount of credit exposure to clients or to a group of connected clients, constituting by size the top ten loan exposure in the total loan portfolio, accounting for 46,2%. In accordance with chapter IV paragraph 26 of the Regulation on Large Exposures No 109 of April 5, 2019, exceeding the limit of the said indicator shall not be considered a breach if the bank maintains an additional own funds requirement on the relevant surplus and the bank meets these requirements.
All banks also complied with the limit of dominance in the banking market, being under the 35% limit of this indicator according to the size of individuals’ deposits.
During 2023, the National Bank of Moldova (NBM) continued the activities related to the elaboration and updating of secondary normative acts for the implementation of Law No 202/2017 on the activity of banks and promotion of Basel III requirements.
In this context, pursuant to DEB of the NBM No 125/2023 amendments have been made to Regulation No 292/2018 on requirements regarding the members of the governing body of the bank, the financial holding company or mixed holding, the heads of a branch of a bank from another state, the persons holding key positions and the liquidator of the bank in liquidation process. The amendments contain clarifications with regard to the applicability of the elements of the interview procedure, including provisions on the mandatory interview by the National Bank of Moldova of the persons nominated to the positions of the head of the bank's branch in another state, the chief accountant, the financial director of the bank/branch of the bank in another state, as well as the head of the bank's control function.
In addition, pursuant to DEB of the NBM No 195/2023, amendments have been made to Regulation No. 147/2019 on branches and secondary offices of banks, which provides for the improvement of the existing regulatory framework in the context of the digitisation of business processes related to the supervision of banks, including the presentation of information on branches and secondary offices through the IT solutions of the National Bank of Moldova.


