Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!


Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!
Cele mai populare rapoarte statistice:
Banca Naţională şi membrii organelor de conducere ale acesteia sunt independenţi în exercitarea atribuţiilor stabilite de lege şi nu pot solicita şi nici accepta instrucţiuni de la autorităţile publice sau de la orice altă autoritate.
Banca Naţională informează publicul despre evoluția inflației anuale, strategia de politică monetară,rezultatele analizei macroeconomice, evoluţiei pieţei financiare şi informaţia statistică, inclusiv privind masa monetară, acordarea creditelor, balanţa de plăţi şi situaţia pieţei valutare.
Pentru asigurarea şi menţinerea stabilităţii preţurilor pe termen mediu, Banca Naţională a Moldovei menţine inflaţia (măsurată prin indicele preţurilor de consum) la nivelul de 5.0 la sută anual cu o posibilă abatere de ± 1.5 puncte procentuale, fiind considerat nivelul optim pentru creşterea şi dezvoltarea economică a Republicii Moldova pe termen mediu.
Stabilitatea financiară se realizează prin consolidarea rezilienței sistemului financiar, limitarea efectului de contagiune și diminuarea acumulării de riscuri sistemice, contribuind, astfel, la sustenabilitatea sectorului financiar și creșterea economică.
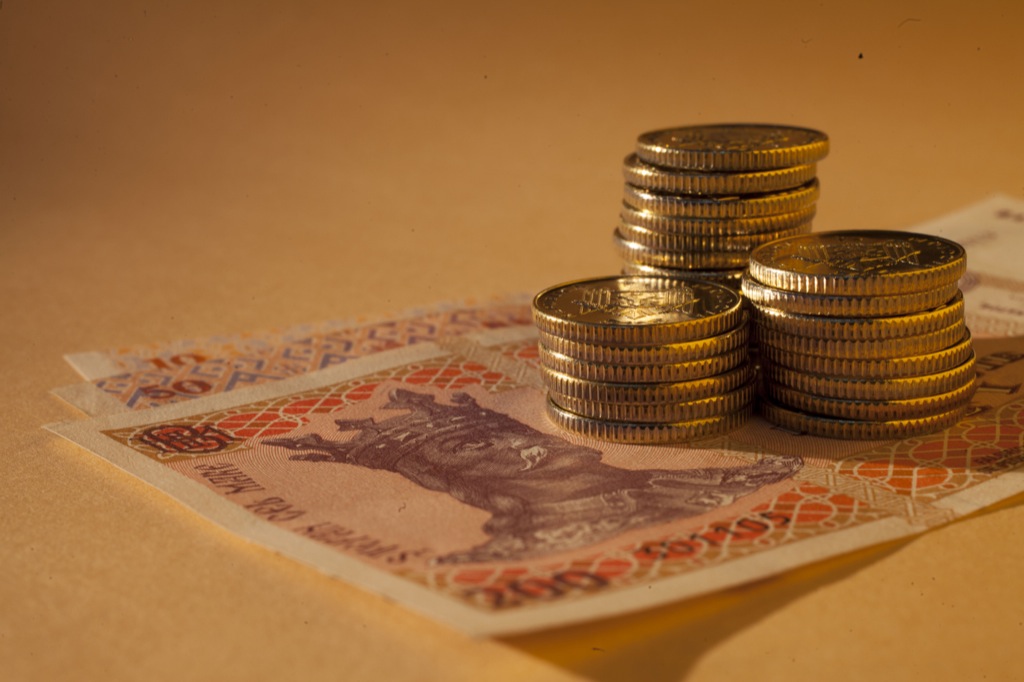
Banca Naţională a Moldovei, are dreptul exclusiv de a emite pe teritoriul Republicii Moldova bancnote şi monede metalice ca mijloc de plată. BNM pune în circulaţie bancnote şi monede metalice, prin intermediul sistemului bancar.
Banca Naţională este unica instituţie care efectuează licenţierea, supravegherea şi reglementarea activităţii instituţiilor financiare.
Banca Națională supraveghează sistemul de plăţi în Republica Moldova şi promovează funcţionarea stabilă şi eficientă a sistemului automatizat de plăţi interbancare.
Banca Naţională este o persoană juridică publică autonomă şi este responsabilă faţă de Parlament.
BNM publică statistici privind masa monetară, sectorul bancar, balanța de plăți, situația pieței valutare, etc. pentru a asigura transparența în procesul de elaborare și adoptare a deciziilor BNM, a asigura continuitatea în comunicare și predictibilitatea BNM pe piață, pentru sporirea credibilității BNM în calitate de bancă centrală dar și pe piața financiar-bancară din Republica Moldova.
The financial situation of the banking sector remains solid, reflecting the constant efforts of the National Bank of Moldova (NBM) to strengthen stability and confidence in the banking system.
According to data reported by banks, in the first semester of 2026, the banking sector recorded increases in assets, own funds, own funds ratio, loans, deposits from individuals, and deposits from legal entities, confirming the performance and confidence in the banking system. At the same time, banks continued to fully comply with prudential requirements, maintaining key indicators at an adequate level and demonstrating a strong ability to adapt and strengthen their capital.
At the same time, the National Bank of Moldova continued to promote important reforms in the areas of banking regulation and legislative harmonisation, in line with European Union standards and Basel III requirements, contributing to the modernisation of the financial system and the advancement of the Republic of Moldova’s European integration process.
As of 30 June 2026, the situation in the banking sector, as reflected in the reports submitted by the banks, showed the following trends:
Total assets amounted to MDL 202,022 million, increasing by 6.4% (MDL 12,140 million) during the first semester of 2026.
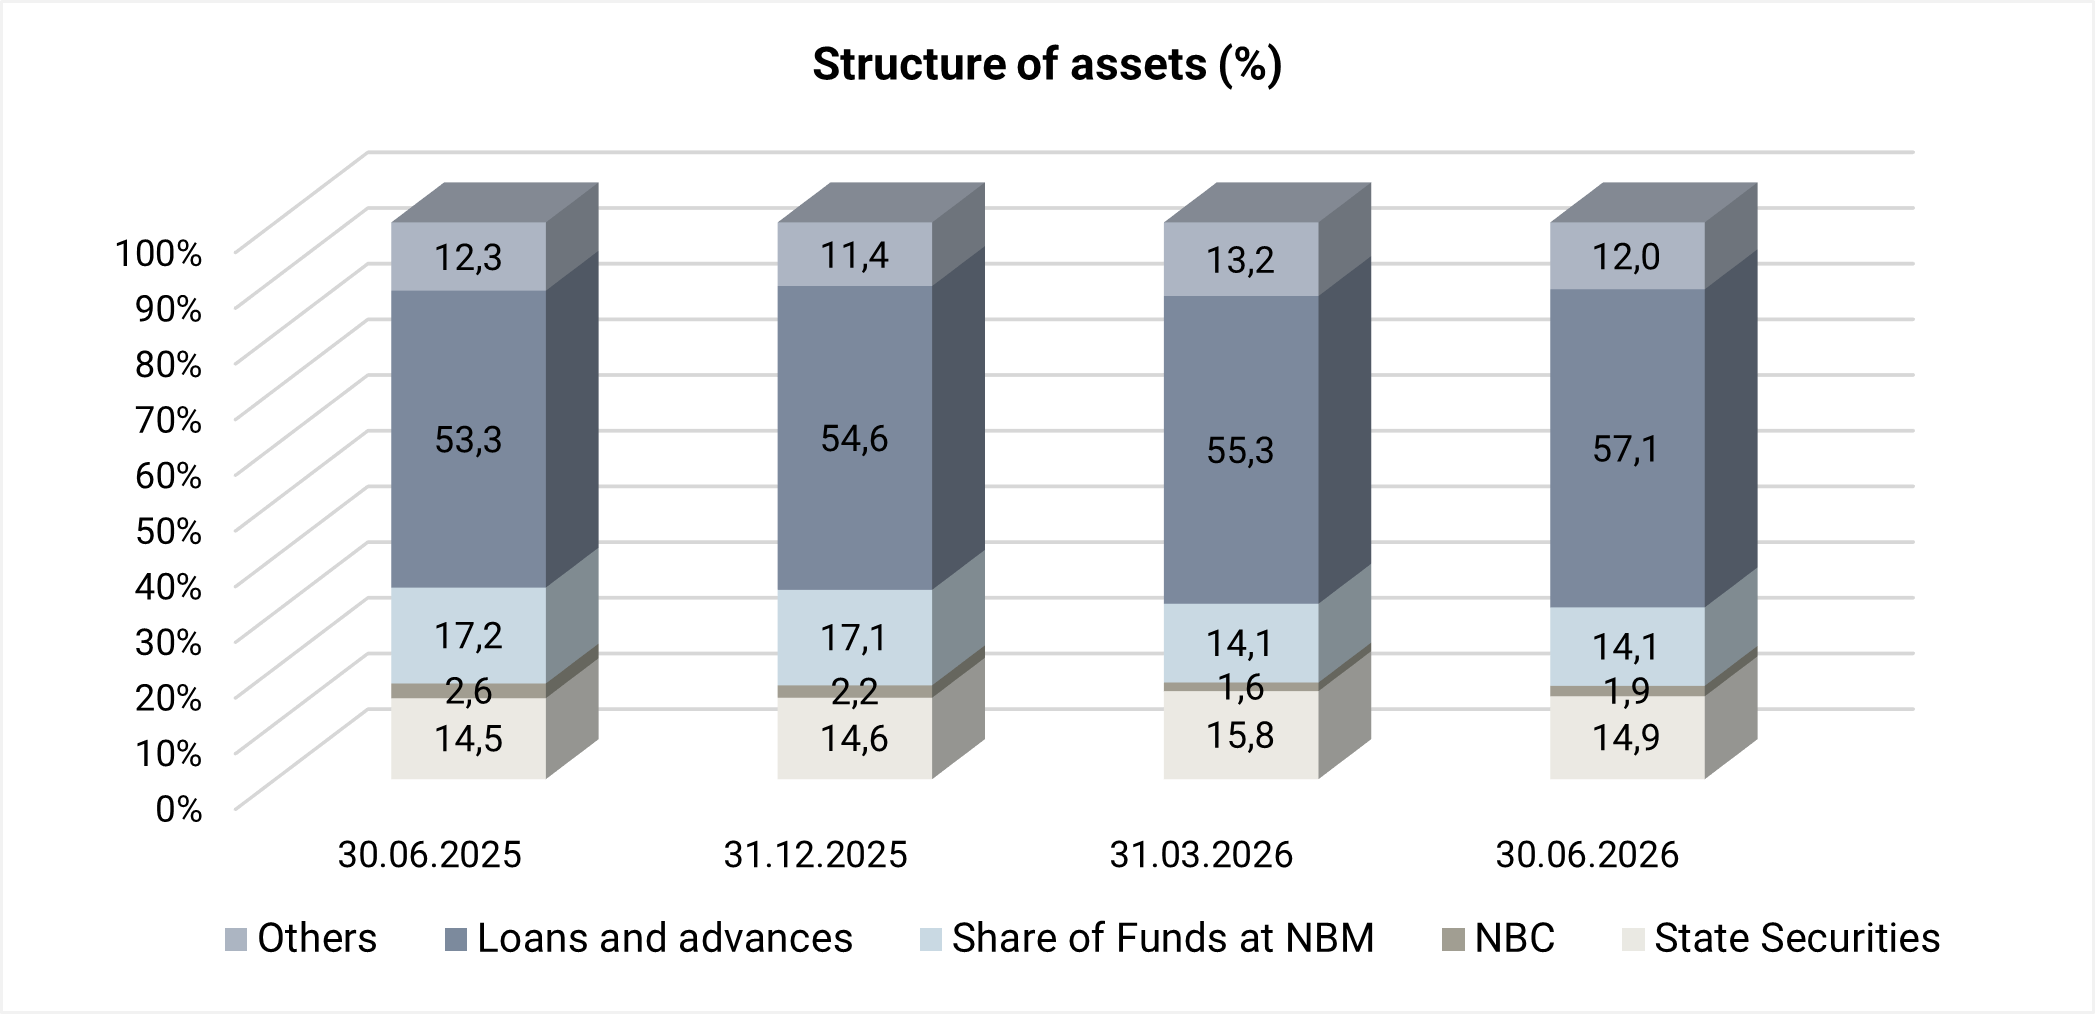
In the asset structure, the largest share was held by loans and advances at amortised cost, which amounted to 57.1% (MDL 115,442.2 million), followed by banks’ investments in state securities and NBM certificates —16.8% (MDL 33,868.8 million), and the share of funds placed with the NBM —14.1% (MDL 28,462.3 million) — and the share of other assets (cash, funds in other banks, tangible assets, intangible assets, etc.) —12% (MDL 24,248.7 million).
The gross (prudential) balance of loans accounted for 56.6% of total assets, or MDL 114,321.1 million, increasing by 11.7% (MDL 11,936 million) during the period under review.
The largest share of the total loan portfolio, in terms of risk distribution by sector, was accounted for by loans granted for the purchase/construction of real estate – 25.3% (MDL 28,964.9 million), loans granted to trade – 20.3% (MDL 23,169.5 million), and consumer loans – 18.7% (MDL 21,428.6 million).
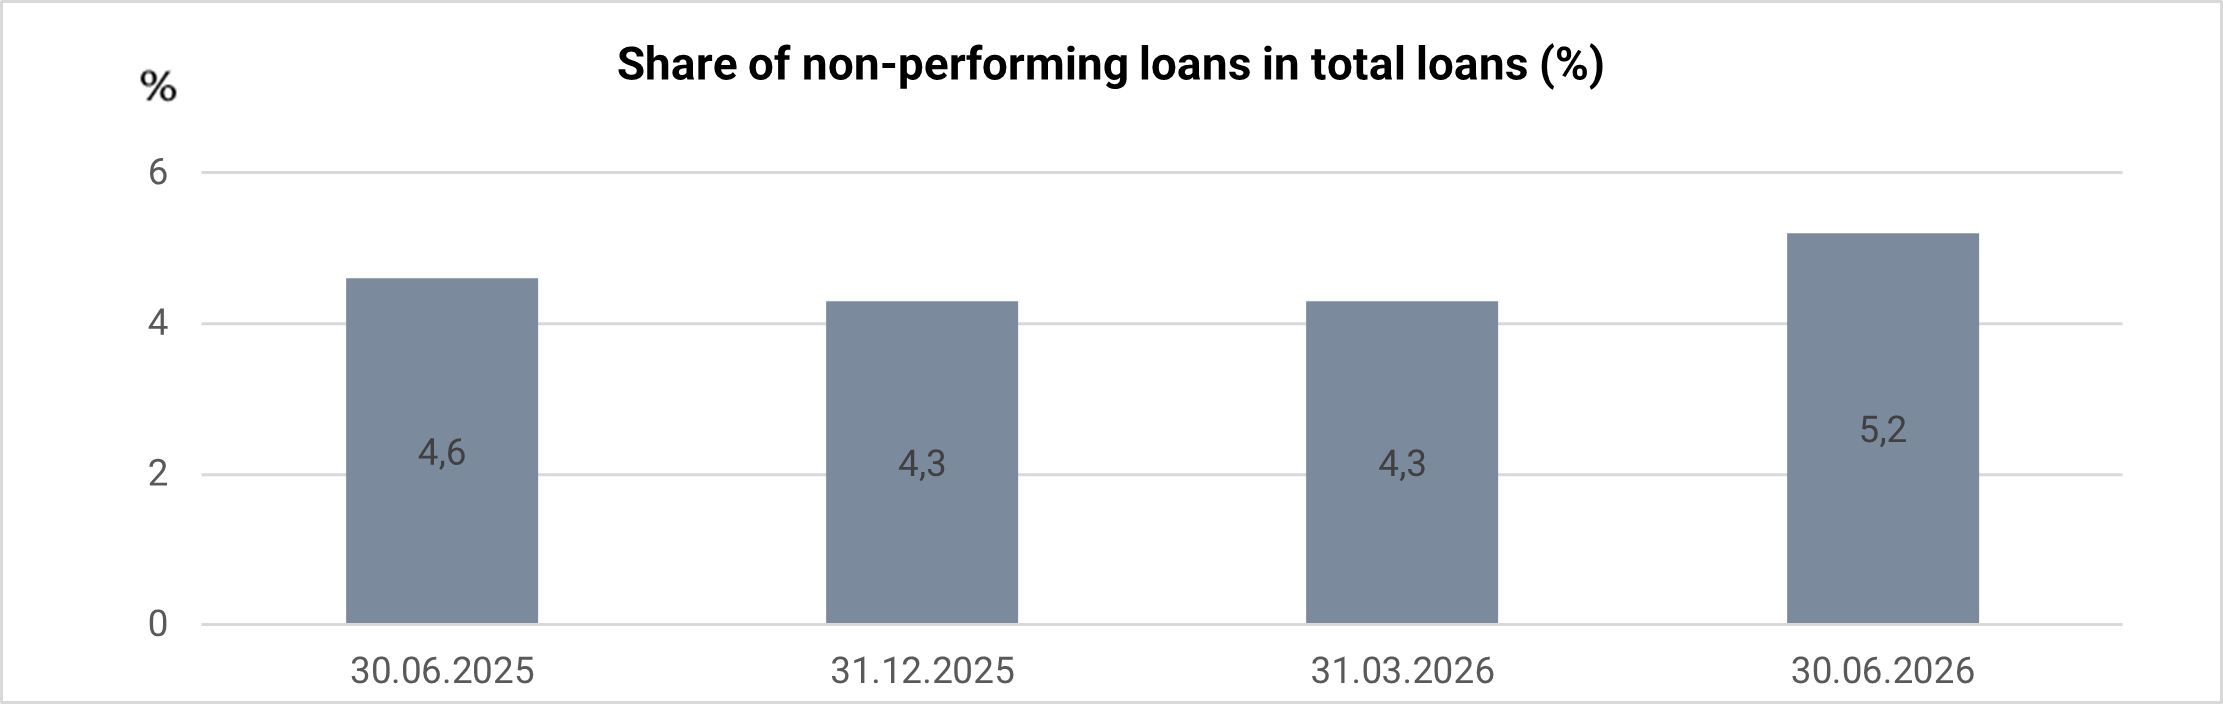
The share of non-performing loans in total loans (IFRS) was 1.4%, and the share of non-performing loans in total loans (prudential) was 5.2%.
At the same time, the share of expired loans (loans with payments more than 30 days past due) stood at 1.4%.
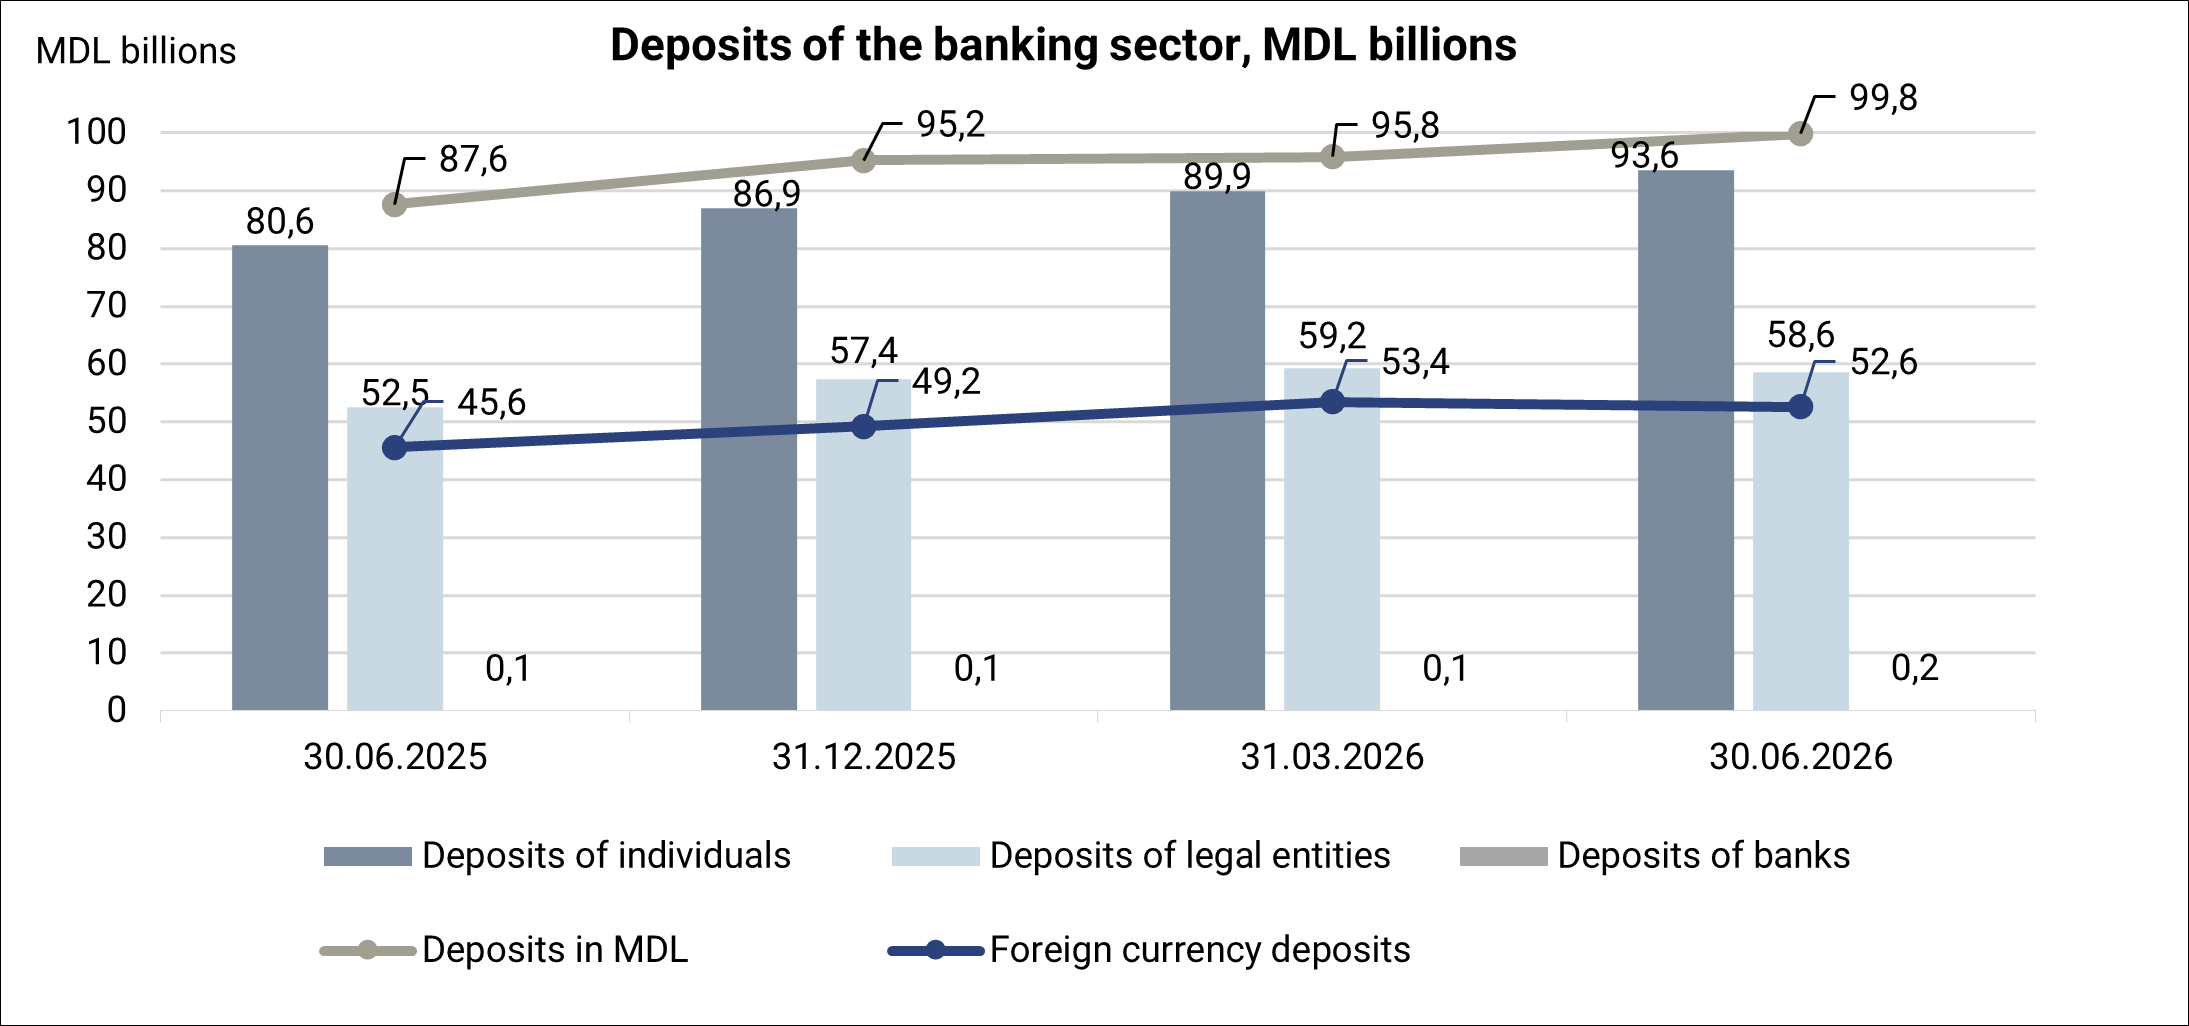
The total balance of deposits increased compared to the end of the previous year by MDL 8,002.2 million, or 5.5%, reaching MDL 152,425 million (deposits of individuals accounted for 61.4% of total deposits, deposits of legal entities—38.5%, and deposits of banks - 0.1%), as a result of an increase in the deposits of individuals by MDL 6,740.3 million (7.8%), to MDL 93,608 million, and in the balance of deposits of legal entities by MDL 1,204.7 million (2.1%), reaching MDL 58,643.1 million. In addition, deposits of banks increased by MDL 57.2 million (49.1%), reaching MDL 173.9 million.
Of total deposits, 65.5% were in MDL, with the balance increasing by MDL 4,560.8 million (4.8%) compared to the end of the previous year and totalling MDL 99,802.9 million as of 30 June 2026. Respectively, foreign currency deposits accounted for 34.5% of total deposits, their balance also increasing during the first semester of 2026 by MDL 3,441.4 million (7%), amounting to MDL 52,622.1 million.
As of 30 June 2026, according to data provided by the banks, the banking sector’s profit totalled MDL 2,355.8 million, an increase of MDL 300.1 million (14.6%) compared to the same period of the previous year, primarily as a result of an increase in interest income of MDL 1,163.3 million (22.4%), to MDL 6,353.6 million, due to a rise in income from lending activities of MDL 854.9 million (22.4%), to MDL 4,673 million.
Profitability indicators point to a stable and efficient banking sector, with solid profitability and a good resource utilisation capacity. Thus, return on assets was 2.3%, and return on equity was 14.7%.
During the first semester of 2026, banks maintained their liquidity indicators at a high level, above the regulatory limits. Accordingly, all banks complied with the prudential liquidity indicators.
As of 30 June 2026, the net stable funding ratio (reported quarterly), which represents the ratio between the bank’s available stable funding and the required stable funding, stood at 163.7% (limit ≥ 100%). This ratio ranged from 144.9% to 249.8%, depending on the bank.
The liquidity coverage ratio (LCR) by sector stood at 263.6% (limit ≥ 100%), ranging from 152.6% to 797%, depending on the bank.
According to reports submitted by banks as of 30 June 2026, the total own funds ratio for the banking sector stood at 24.3%, an increase of 1 percentage point compared to the end of the previous year, due to a rise in own funds of MDL 2,980.5 million (12.7%), accompanied by an increase in total risk exposure of MDL 8,130 million (8.1%) (due to growth in loans). This ratio ranged from 21% to 37.1%, depending on the bank. All banks complied with the “Total own funds ratio” requirement (limit ≥ 10%).
Banks also complied with the requirement related to the “Total own funds ratio” indicator, taking into account capital buffers.
As of 30 June 2026, total own funds amounted to MDL 26,508 million, an increase of 12.7% (MDL 2,980.5 million). The increase in own funds was primarily driven by certain banks recognising eligible profits following their general shareholders’ meetings.
As of 30 June 2026, the banks complied with the prudential indicators on large exposures and exposures to their related persons.
During the reporting period, banks complied with the limit on the dominant position in the banking market, remaining below the 35% limit for this indicator in terms of total assets and individuals’ deposits, with the exception of one bank. This bank exceeded the 35% limit for its dominant position based on total assets, which stood at 36.1%, while its dominant position in the banking market based on individuals’ deposits stood at 36.4%.
During the second quarter of 2026, the National Bank of Moldova (NBM) continued its work on drafting and updating secondary normative acts for the implementation of Law No 202/2017 on the activity of banks, aligning them with the EU acquis, promoting Basel III requirements and best practices in the field.
Therefore, by Decision No 119/2026 of the Executive Board of the NBM, the Regulation on the treatment of Credit Valuation Adjustment risk for banks was approved, establishing new methods for calculating own funds requirements for CVA risk, by applying a new standardised, basic, and simplified approach, as well as a new treatment of eligible hedges against risk for the purpose of calculating own funds requirements for CVA risk based on the aforementioned methods (the amendments will enter into force on 1 July 2027). At the same time, the approval of the aforementioned regulation necessitated an amendment to the Instruction on submission by banks of COREP reports for supervisory purposes, approved by NBM Executive Board Decision No 117 of 24 May 2018. Consequently, NBM Executive Board Decision No 120/2026 revised the wording of template C 25.00 CREDIT VALUATION ADJUSTMENT (CVA) RISK. The development of this template was prompted by new EU regulations regarding capital requirements, which must be established in such a way as to absorb losses arising from credit valuation adjustment risk.
Furthermore, following the approval of Regulation No 311/2025 on own funds requirements for operational risk, which introduced the new standardised approach, it became necessary to amend the reporting forms. Thus, by Decision No 121/2026 of the Executive Board of the NBM, the Instruction on submission by banks of COREP reports for supervisory purposes (approved by NBM Executive Board Decision No 117 of 24 May 2018) was amended, which will contribute to the unified reporting by banks of data and information related to own funds requirements for operational risk, as well as losses from operational risk.
In order to ensure the full transposition of the provisions related to credit risk mitigation techniques set out in EU Regulation No 575/2013, Decision No 143/2026 of the Executive Board of the NBM was approved, amending Decision No 112/2018 of the Executive Board of the NBM on the approval of the Regulation on credit risk mitigation techniques of banks. Accordingly, as of 1 July 2027, in addition to the standardised approach, banks will be able to apply the internal ratings-based (IRB) approach to determine the effect of credit risk mitigation techniques (eligible collateral) for the purpose of calculating capital requirements.


