Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!


Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!
Cele mai populare rapoarte statistice:
Banca Naţională şi membrii organelor de conducere ale acesteia sunt independenţi în exercitarea atribuţiilor stabilite de lege şi nu pot solicita şi nici accepta instrucţiuni de la autorităţile publice sau de la orice altă autoritate.
Banca Naţională informează publicul despre evoluția inflației anuale, strategia de politică monetară,rezultatele analizei macroeconomice, evoluţiei pieţei financiare şi informaţia statistică, inclusiv privind masa monetară, acordarea creditelor, balanţa de plăţi şi situaţia pieţei valutare.
Pentru asigurarea şi menţinerea stabilităţii preţurilor pe termen mediu, Banca Naţională a Moldovei menţine inflaţia (măsurată prin indicele preţurilor de consum) la nivelul de 5.0 la sută anual cu o posibilă abatere de ± 1.5 puncte procentuale, fiind considerat nivelul optim pentru creşterea şi dezvoltarea economică a Republicii Moldova pe termen mediu.
Stabilitatea financiară se realizează prin consolidarea rezilienței sistemului financiar, limitarea efectului de contagiune și diminuarea acumulării de riscuri sistemice, contribuind, astfel, la sustenabilitatea sectorului financiar și creșterea economică.
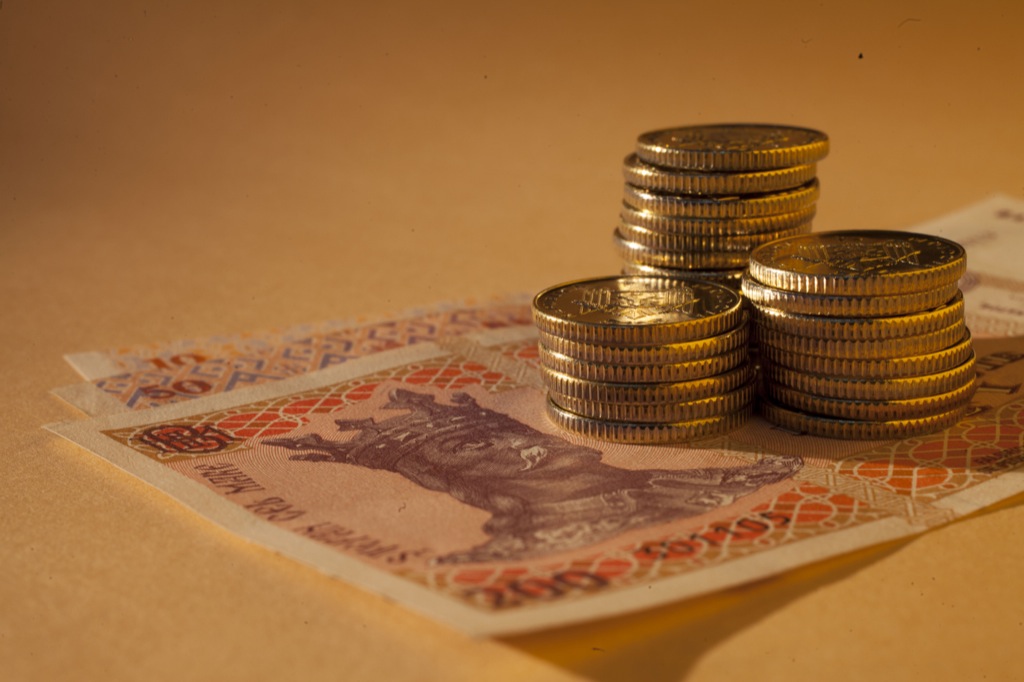
Banca Naţională a Moldovei, are dreptul exclusiv de a emite pe teritoriul Republicii Moldova bancnote şi monede metalice ca mijloc de plată. BNM pune în circulaţie bancnote şi monede metalice, prin intermediul sistemului bancar.
Banca Naţională este unica instituţie care efectuează licenţierea, supravegherea şi reglementarea activităţii instituţiilor financiare.
Banca Națională supraveghează sistemul de plăţi în Republica Moldova şi promovează funcţionarea stabilă şi eficientă a sistemului automatizat de plăţi interbancare.
Banca Naţională este o persoană juridică publică autonomă şi este responsabilă faţă de Parlament.
BNM publică statistici privind masa monetară, sectorul bancar, balanța de plăți, situația pieței valutare, etc. pentru a asigura transparența în procesul de elaborare și adoptare a deciziilor BNM, a asigura continuitatea în comunicare și predictibilitatea BNM pe piață, pentru sporirea credibilității BNM în calitate de bancă centrală dar și pe piața financiar-bancară din Republica Moldova.
The financial situation of the banking sector, according to the data given by the banks, is represented by the assets increase, loans, own funds, individuals’ deposits, legal entities deposits.
The related profit of the act comparing to the similar period of the previous year has decreased mainly as a result of diminishing the interest incomes. The interest incomes decreased, mainly, because of diminishing the incomes achieved from investments in debt securities (VMS, CBN), of the incomes from funds positioned at NBM (mandatory reservations) and from incomes attained from the lending activity.
Non-performing loans in absolute value and expired loans decreased. Therefore, the portfolio quality indicators registered an improvement compared to the end of the previous year.
At the same time, the rate of own funds decreased as a result of the increase in the total amount of risk exposure by MDL 6,155.2 million (8.7%) (increase in loans).
As of 30.06.2024, 11 banks authorized by the National Bank of Moldova were active in the Republic of Moldova.
On 30.06.2024, the banking sector state, reflected in reports’ base presented by the banks, has registered the following tendencies:
The total assets represented MDL 161297,1 million, increasing during the first semester of the 2024 with 4,8% (MDL 7442,5 million)
In the structure of assets, the largest share was returned to the balance sheet item "Loans and advances at amortized cost", which constituted 42.6% (MDL 68,673.9 million), increasing by 2.0 percentage points (p.p.) compared to the end of the previous year. The share of assets placed with the NBM constituted 25.0% (MDL 40,382.5 million), being down by 1.1 p.p., and the share of banks' investments in state securities and NBM certificates represented 18.2% (MDL 29 372.6 million), being down by 1.5 p.p. The rest of the assets, which constitute 14.2% (MDL 22,868.1 million), are maintained by banks in other banks in cash, tangible assets, intangible assets, etc. Their share increased by 0.7 p.p. compared to the end of 2023.
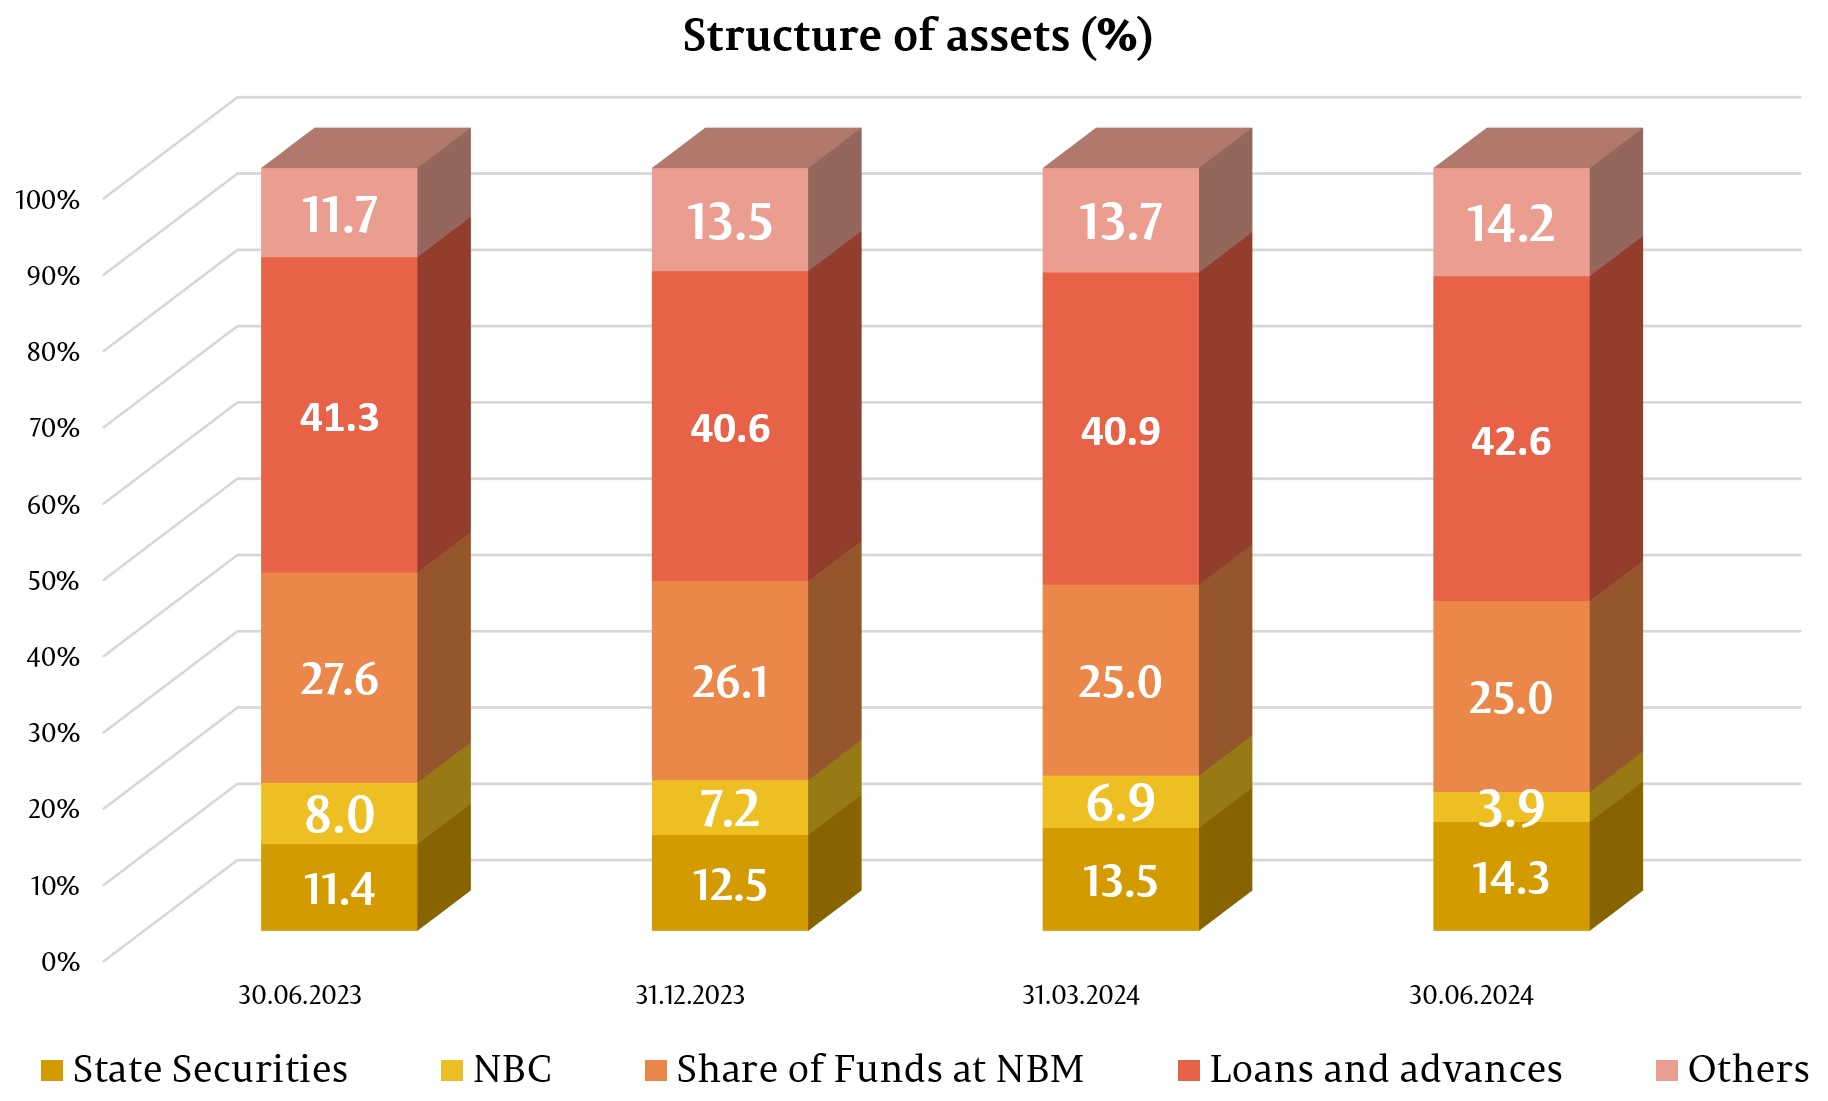
The gross (prudential) loan balance amounted to 43.2% of total assets or MDL 6,9613.8 million, increasing by 8.9% (MDL 57,187.3 million) during the analyzed period.
The highest increase was recorded in loans granted for the purchase/construction of real estate - by MDL 1,654.8 million (12.5%) up to MDL 14,937.1 million, consumer loans by MDL 1,384.7 million (12.4%) up to MDL 12,584.6 million, loans granted in services sector - by MDL 584.1 million (26.9%) up to MDL 2,752.4 million, and loans granted for trade - by MDL 5720 million (4,810.6 million.
At the same time, the largest decrease during the first semester of 2024 was recorded in other loans - by MDL 183.6 million (8.1%) up to MDL 2103.5 million.
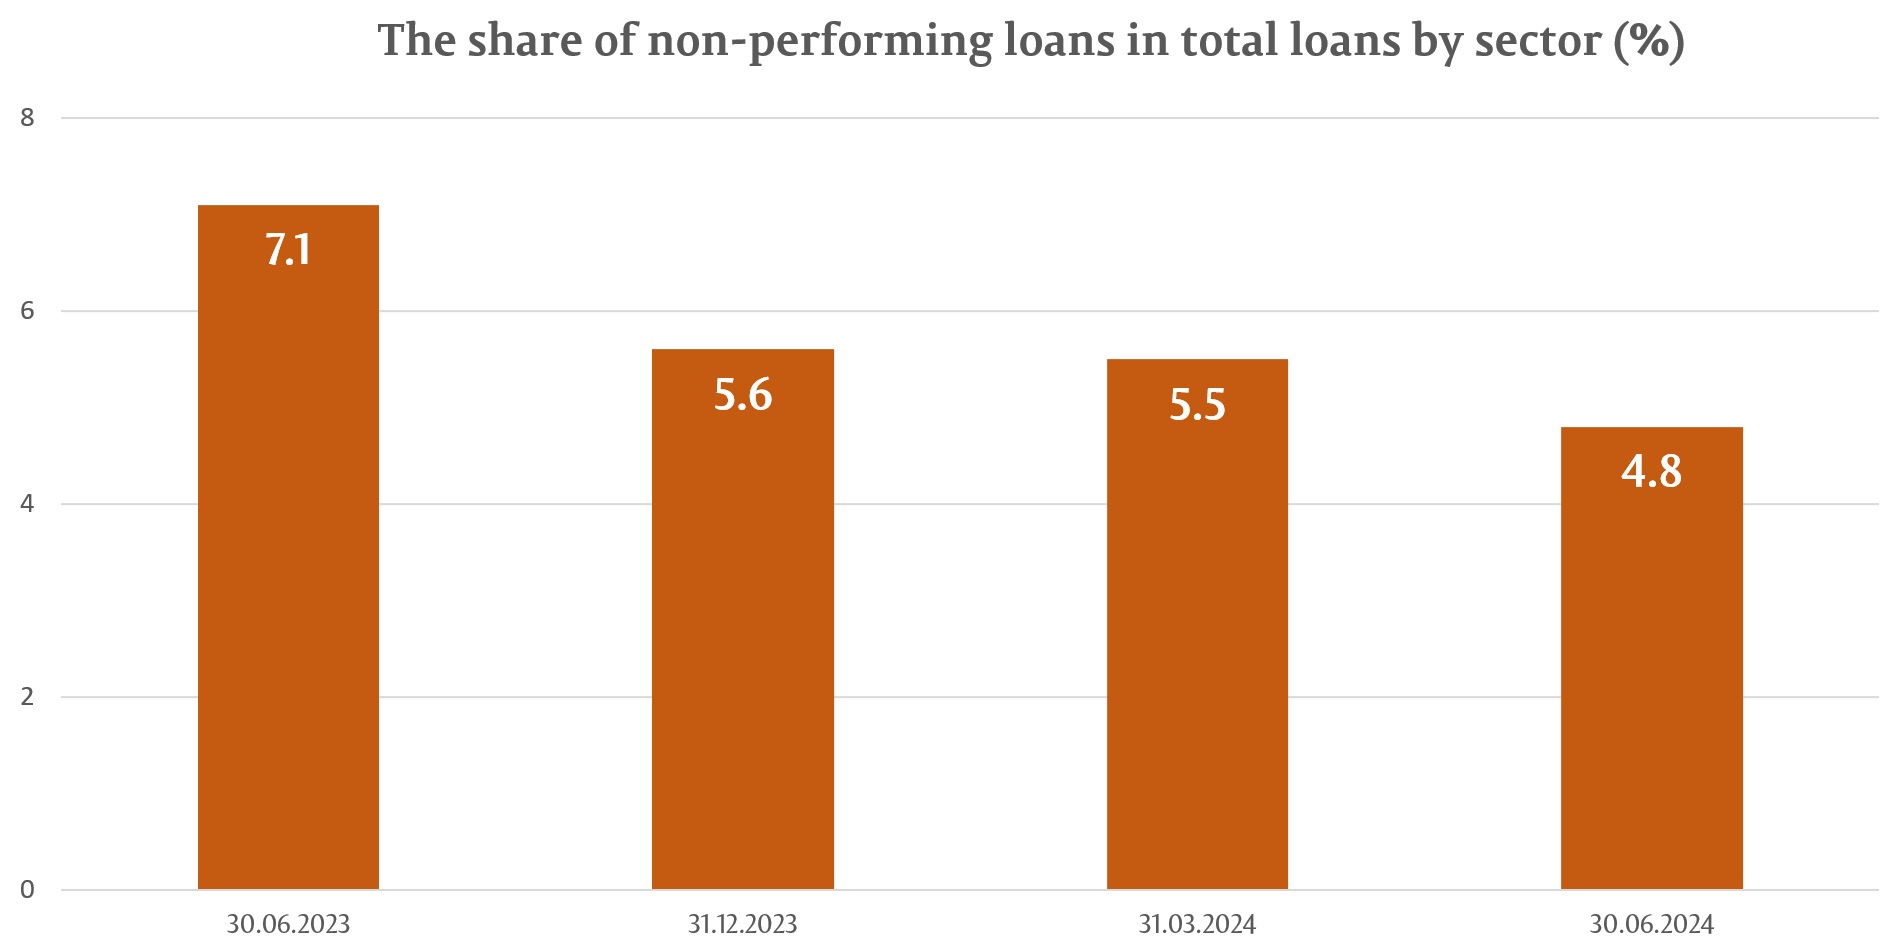
During the reference period, the share of non-performing loans (substandard, suspicious, and compromised) in total loans decreased by 0.8 p.p., constituting 4.8% as of June 30, 2024, ranging from 3.4% to 6.0%, depending on the bank.
At the same time, non-performing loans in absolute value decreased by 4.8% (MDL 171.5 million) to MDL 3,375.7 million.
Additionally, overdue loans decreased by 19.9% (406.2 million MDL) to MDL 1632.7 million. The share of overdue loans in total loans amounted to 2.4%, decreasing by 0.9 p.p. compared to 31.12.2023, ranging from 0.9% to 5.1%, depending on the bank.
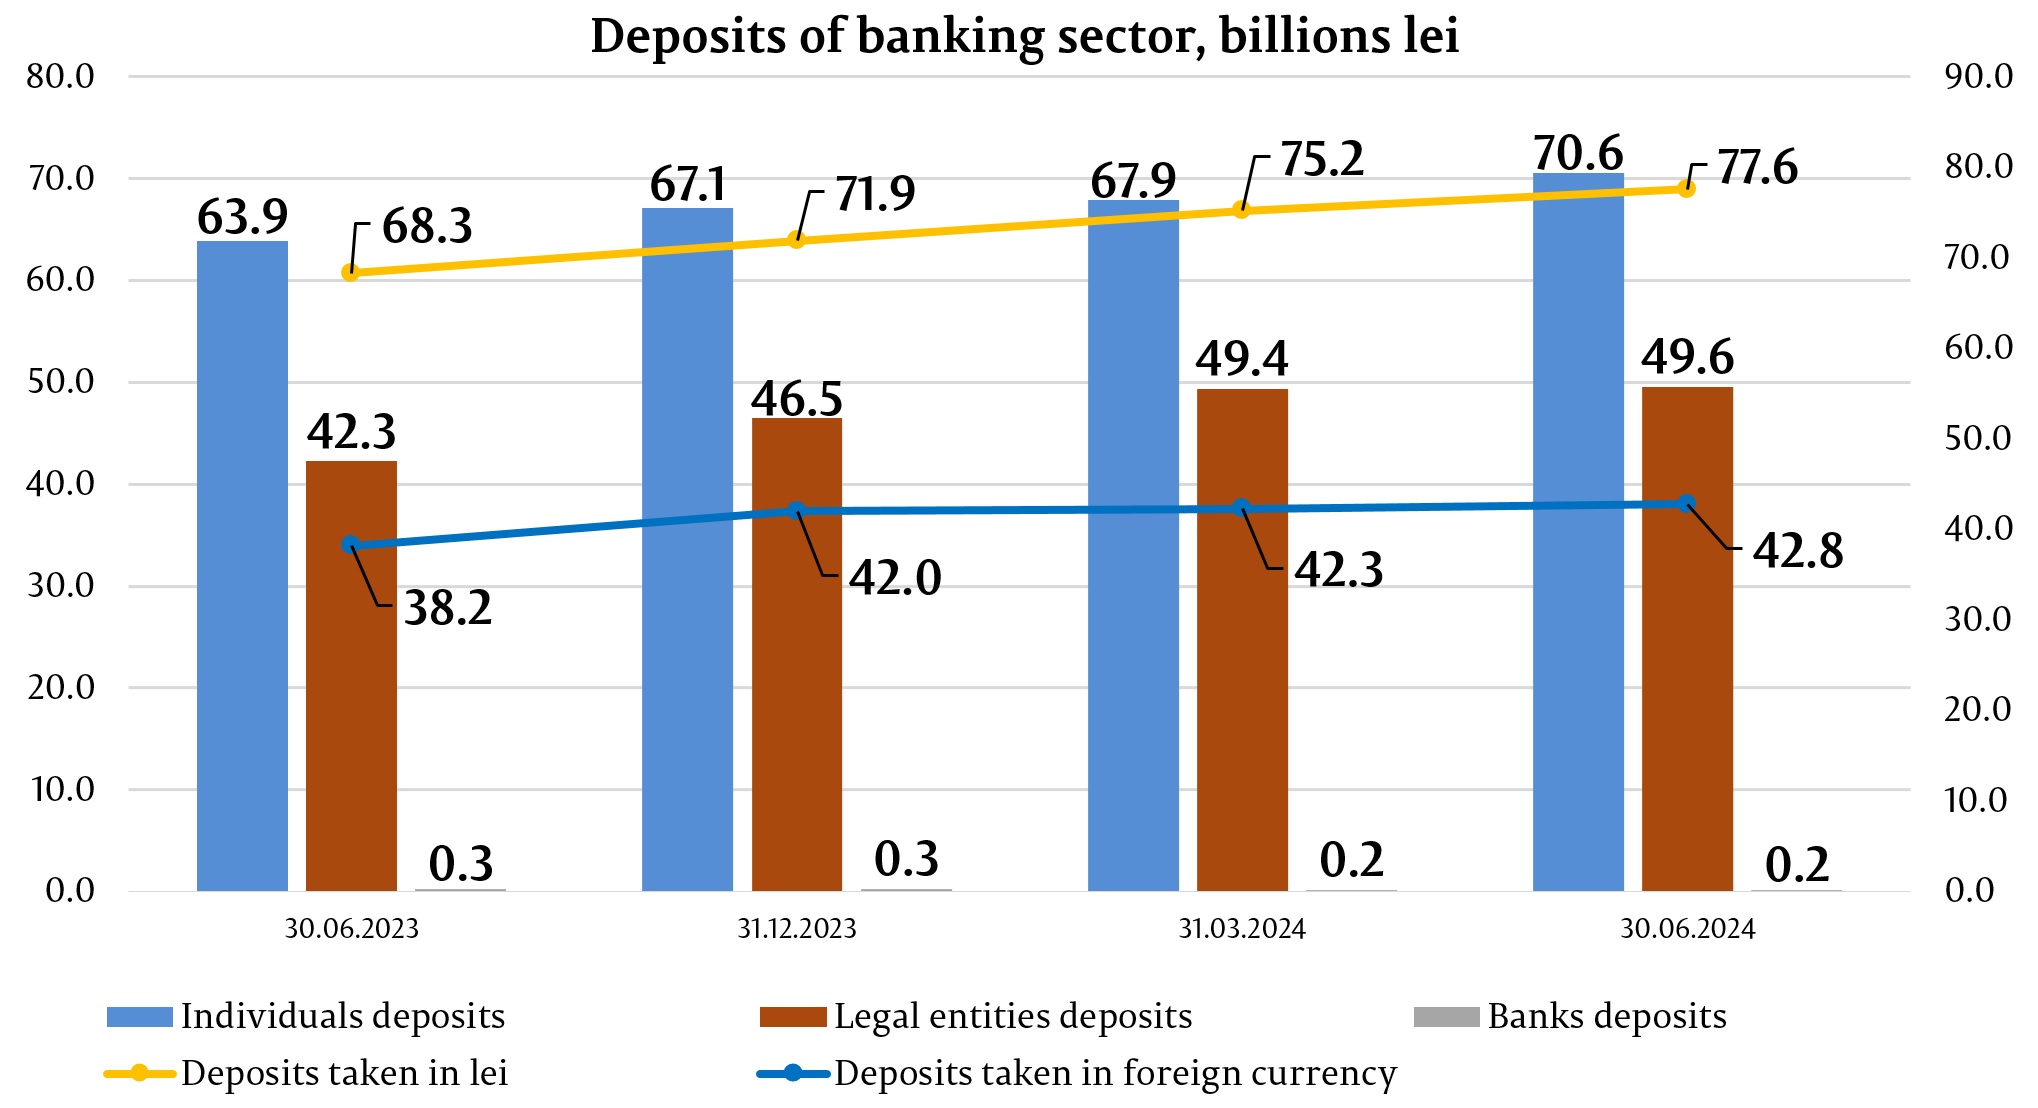
At the same time, during the reference period, the total balance of deposits increased by MDL 6,591.9 million or by 5.8%, amounting to MDL 120,455.7 million (deposits of individuals accounted for 58.6% of total deposits, deposits of legal entities – 41.2%, and bank deposits - 0.2%). This increase was due to the rise in the balance of legal entities' deposits by 3,140.4 million MDL (6.8%) up to MDL 49,648.4 million and deposits of individuals by MDL 3,545.0 million (5.3%) up to MDL 70,633.7 million.
Within total deposits, 64.5% were accounted for by deposits in MDL, with the balance increasing by MDL 5,733.5 million (8.0%) compared to the end of the previous year, amounting to MDL 77,638.1 million as of June 30, 2024. Deposits in foreign currency accounted for 35.6% of total deposits, their balance increased during the reference period by MDL 858.5 million (2.0%), amounting to MDL 42,817.7 million MDL.
As of June 30, 2024, the profit in the banking sector amounted to MDL 1,743.8 million, decreasing by MDL 672.2 million MDL (39.2%) compared to the same period of the previous year.
The decrease in profit was due to the reduction in interest income with MDL 2086.5 million (31.8%). At the same time, income from exchange rate differences increased by MDL 261.1 million (36,3%) and income from fees and commissions by MDL 127.5 million (4.9%). Moreover, interest expenses decreased by MDL 1,142.0 million (45.0%), while non-interest expenses (expenses related to fees and commissions, administrative expenses, provisions, impairment of financial and non-financial assets, etc.) increased by MDL 147.6 million (3.7%).
Total revenues amounted to MDL 7,249.6 million, down by MDL 1,666.6 million (18.7%) compared to the same period of the previous year, of which interest income accounted for 61.8% (MDL 4478.4 million) and non-interest income – 38.2% (MDL 2,771.2 million).
At the same time, total expenses amounted to MDL 5,505.8 million, decreasing by MDL 994.4 million (15.3%) compared to the same period of the previous year, of which interest expenses amounted to MDL 1,374.9 million (25,0% of total expenses), while non-interest expenses - MDL 4,130.9 million (75.0% of total expenses).
As of June 30, 2024, the return on assets amounted to 2.2%, decreasing by 0.6 p.p. compared to the end of the previous year, and the return on capital amounted to 13.0%, down by 3.2 p.p. year-on-year.
During the first semester of 2024, banks continued to maintain cash ratios at a high level, above the regulated limits.
Therefore, the value of the long-term cash ratio (liquidity principle I) amounted to 0.70 (limit ≤1), ranging from 0.26 to 0.87 depending on the bank, increasing by 0.01 compared to the end of 2023.
Cash Principle III, which is the ratio of adjusted actual cash resources to required cash in each maturity band which should not be less than 1, was also respected by all banks, ranging from 1.38 in the maturity band up to one month to 159.68 in the maturity band between one month and 3 months.
The cash coverage ratio by sector amounted to 260.9% (limit ≥100%), ranging from 160.4% to 886.3%, decreasing by 21.4 p.p. by the end of 2023.
According to the reports submitted by banks as of June 30, 2024, the total capital ratio in the banking sector recorded the value of 28.8%, down by 1.2 p.p. compared to the end of the previous year, ranging between 22.2% and 60.6%. All banks complied with the "Capital ratio of total own funds (≥10%)".
All banks also complied with the requirement of the "Total capital ratio" indicator, considering capital buffers.
As of June 30, 2024, total own funds amounted to MDL 21,855.5 million, recording an increase of 4.6% (MDL 935.7 million). The increase in own funds was mainly determined by some banks reflection of eligible profit after deploying general meetings with the shareholders and after attaining the NBM permission regarding the embedding in own funds of the achieved funds.
As of 30th of June 2024, the banks complied with the prudential indicators regarding big exposures and the exposures with their related people, except one bank, which registered an overflow of 30% limit of the aggregated value sum of the exposures from loans toward clients or a group of clients connected, that represent, according to the size, the first ten exposures from loans in the total portfolio of loans, the 53.3%. According to the IV chapter, point 26 of the Regulation, regarding large exposures no. 109 from the 5th April 2019, exceeding the limit of the aforementioned indicator shall not be considered a breach if the bank maintains additional own funds on that excess and meets these requirements.
All banks also complied with the banking market dominance limit, being below the 35% threshold for this indicator by the size of retail deposits and assets, except for one bank. This bank exceeded the 35% limit of the banking market dominance by asset size, reaching 36.0%, and the dominance in the banking market by the size of retail deposits amounted to 35.0%, being at the established limit (≤ 35%).
During the second quarter of 2024, the National Bank of Moldova (NBM) continued activities related to the development and updating of secondary regulatory acts for the implementation of Law No. 202/2017 on the activity of banks and the promotion of Basel III requirements.
In this context, by HCE of the NBM No. 177 of 27/06/2024, amendments were made to the Directive regarding the banks presenting the COREP reports aiming supervision, approved by the Resolution of the Executive Board of the National Bank of Moldova no. 117/2018.
This (COREP) instruction was supplemented with provisions related to a new instrument for cash supervision (liquidity on maturity bands) that will allow the NBM to monitor the cash of banks more effectively. The Form C 66.01 Maturity Bands is a report on the basis of which banks will present information about the future contractual cash flows generated by all balance sheet and off-balance sheet elements, such as the stock of unencumbered assets or other sources of financing available to the bank in terms of from a legal and practical point of view, the contingent outflows and the memorandum elements divided into maturity bands. The information provided by the bank will serve as a basis for additional cash monitoring by the NBM in order to ensure, if necessary, through the instruments available to the supervisor, the maintenance of an adequate level of cash assets.
Therefore, the report represents a monitoring instrument of the NBM of entrance and exit contracting cash gaps of the bank for determined time ranges. The monitoring instrument represented by the maturity bands covers the contracting flows and the contingent outflows.
At the same time, we can mention that the report C 66.00 Maturity bands, according to the best European practices, are used at the assessment of the bank cash in case of granting cash assistance in emergency situations.


