Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!


Bine ați venit pe pagină oficială a Băncii Naționale a Moldovei!
Cele mai populare rapoarte statistice:
Banca Naţională şi membrii organelor de conducere ale acesteia sunt independenţi în exercitarea atribuţiilor stabilite de lege şi nu pot solicita şi nici accepta instrucţiuni de la autorităţile publice sau de la orice altă autoritate.
Banca Naţională informează publicul despre evoluția inflației anuale, strategia de politică monetară,rezultatele analizei macroeconomice, evoluţiei pieţei financiare şi informaţia statistică, inclusiv privind masa monetară, acordarea creditelor, balanţa de plăţi şi situaţia pieţei valutare.
Pentru asigurarea şi menţinerea stabilităţii preţurilor pe termen mediu, Banca Naţională a Moldovei menţine inflaţia (măsurată prin indicele preţurilor de consum) la nivelul de 5.0 la sută anual cu o posibilă abatere de ± 1.5 puncte procentuale, fiind considerat nivelul optim pentru creşterea şi dezvoltarea economică a Republicii Moldova pe termen mediu.
Stabilitatea financiară se realizează prin consolidarea rezilienței sistemului financiar, limitarea efectului de contagiune și diminuarea acumulării de riscuri sistemice, contribuind, astfel, la sustenabilitatea sectorului financiar și creșterea economică.
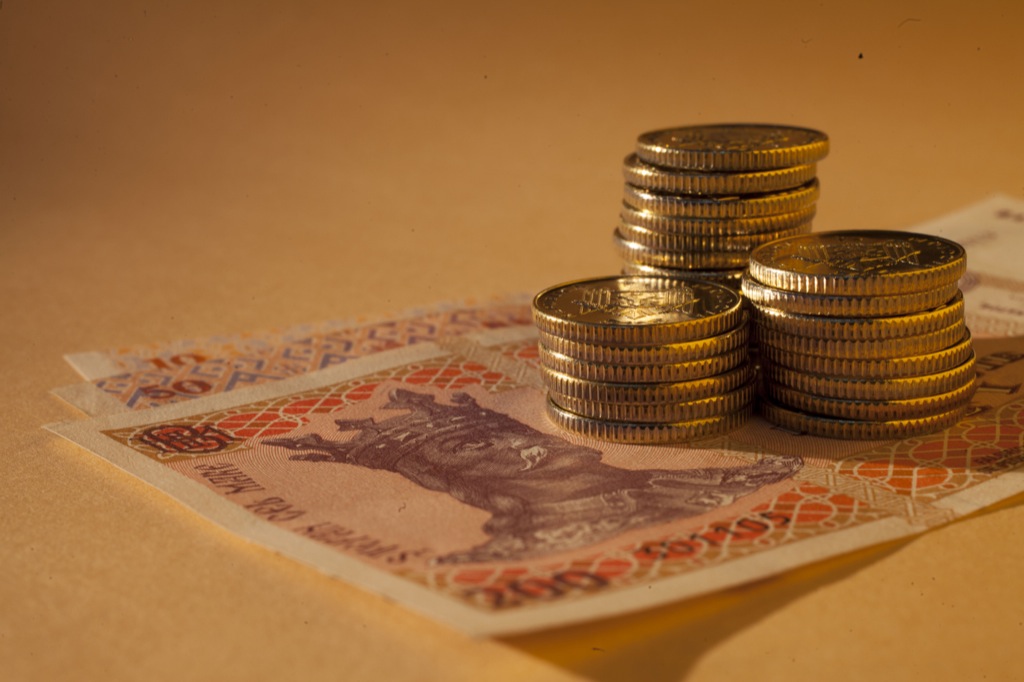
Banca Naţională a Moldovei, are dreptul exclusiv de a emite pe teritoriul Republicii Moldova bancnote şi monede metalice ca mijloc de plată. BNM pune în circulaţie bancnote şi monede metalice, prin intermediul sistemului bancar.
Banca Naţională este unica instituţie care efectuează licenţierea, supravegherea şi reglementarea activităţii instituţiilor financiare.
Banca Națională supraveghează sistemul de plăţi în Republica Moldova şi promovează funcţionarea stabilă şi eficientă a sistemului automatizat de plăţi interbancare.
Banca Naţională este o persoană juridică publică autonomă şi este responsabilă faţă de Parlament.
BNM publică statistici privind masa monetară, sectorul bancar, balanța de plăți, situația pieței valutare, etc. pentru a asigura transparența în procesul de elaborare și adoptare a deciziilor BNM, a asigura continuitatea în comunicare și predictibilitatea BNM pe piață, pentru sporirea credibilității BNM în calitate de bancă centrală dar și pe piața financiar-bancară din Republica Moldova.
Inflation Report no.2, May 2021
Following the downward dynamics of the previous year, in the first quarter of 2021, the annual inflation rate marked the beginning of an upward trajectory. Thus, increasing from 0.2% in January 2021 to 1.5% in March 2021, still being placed below the lower limit of the range of 5.0% ± 1.5 percentage points. The increase in the annual inflation rate in the first three months of the year was mainly supported by the rise in oil prices, the depreciation of the exchange rate and the adjustment of excise duties which led to an acceleration in fuel prices in the domestic market. At the same time, the modest harvest for certain crops from the previous year, the increase in import prices and the intensification of cost pressures led to an increase in food prices on the local market.
At the same time, disinflationary pressures, especially on core inflation, continued to be exerted by negative domestic demand in the context of the effects of the COVID-19 pandemic on the domestic economy. A disinflationary impact on the annual inflation rate was exerted by the decrease in the annual rate of regulated prices as a result of the adjustment of the electricity tariff from February 2021. In the next period, the upward trajectory of the annual CPI rate will continue, mainly due to cost pressures. In this sense, the dynamics of prices in industry outlined a sharp upward trajectory at the beginning of this year. At the same time, the subsequent dynamics of the CPI remain marked by the uncertainty of the timing and magnitude of some tariff adjustments, but also by the impact of weather conditions on food prices on the domestic market.
The beginning of 2021 was highlighted in the world economy by increasing the prospects for the vaccination process against COVID-19, which is more advanced in developed economies, but is practically at the beginning in poorer economies that depend on vaccine donations through the COVAX platform. It also determines growth prospects by country and region, the IMF said in its new report1 that, economic growth will be very fragmented worldwide in 2021. In February-March, the third pandemic wave was registered in the European Union, which led to the tightening of quarantine restrictions. At the same time, the European Union lags behind the advanced savings in vaccination, following the problems of delivery and redistribution of vaccines.
Rising economic outlook has boosted markets, leading to rising commodity and food prices, production, warehousing and transport costs. Thus, in most economies there has been an increase in inflationary pressures related to costs, even if consumer demand continues to be relatively weak. Brent oil prices rose to more than 65 USD as OPEC+ controlled oil supply in line with demand developments since May 2020. At the same time, international quotations for food products increased in March 2021 by 24.6% on an annual basis, reflecting a reduced supply generated by poor harvests.
In the region, the appreciation trend of the Russian ruble as a result of rising oil prices has been flattened by the tightening of the geopolitical fund and the announcement of new sanctions. The Turkish lira also depreciated significantly after a new dismissal of the central bank governor that increased investor distrust in the independence of the monetary authority.
In the context of internal restrictions related to COVID-19, the regional economic climate affected by the pandemic, as well as the adverse conditions for the agricultural sector in the fourth quarter of 2020, the dynamics of economic activity continued to be negative after the sharp decline in previous periods. Thus, in the fourth quarter of 2020, GDP was 3.3% lower than in the same period of 2019, the respective dynamics being, however, higher than anticipated in the Inflation Report no.1, 2021. Therefore, the effect of aggregate demand on prices continued to be negative. At the same time, the seasonally adjusted series reflects a 2.6% increase in GDP compared to the third quarter of 2020. At the same time, along with the agricultural sector, trade and transport registered significant decreases that marked the dynamics of GDP. Construction and the financial sector continued to evolve positively. From the perspective of uses, domestic consumption continued to register a negative dynamic, but it was less pronounced compared to the third quarter of 2020, against the background of the negative dynamics of disposable income of the population in 2020, but also the uncertainty about further developments of the economic situation. A minor positive impact was determined by the investment dynamics. Exports, in the context of a modest external demand, of some restrictions related to COVID-19 in the region, but also of a smaller harvest, continued the negative dynamics from the beginning of 2020. The decrease in domestic demand also led to a negative dynamics of imports in the fourth quarter of 2020. The decline in economic activity against the background of the impact of the restrictions related to COVID-19 led to the continuation of the negative evolution of the economically active population and the employed population. Most of the operational indicators on the dynamics of economic activity since the beginning of this year continued to register a negative dynamics, outlining preconditions for a modest evolution of GDP in the first quarter of 2021.
In January-March 2021, the revenues of the national public budget recorded increases, being 11.1% above the level recorded in the similar period of 2020. National public budget expenditures increased, being 12.1% above the level in the first quarter of 2020. At the same time, on the market of state securities allocated during the first quarter of 2021, interest rates decreased on all types of maturities, except for 2-year government bonds.
In the first quarter of 2021, excessive liquidity amounted to 6.3 billion lei, decreasing compared to the previous quarter by 0.1 billion lei.
The monetary aggregates in the first quarter of 2021 registered a positive dynamics in annual terms, largely determined by the change in the "money in circulation" component and the volume of deposits in the national currency.
During the first quarter of 2021, two meetings of the Executive Board of the National Bank of Moldova on monetary policy decisions took place. Following the assessment of the balance of internal and external risks and the short- and medium-term inflation outlook, the Executive Board of the National Bank of Moldova, at its meetings of January 29, 2021 and March 5, 2021, decided to maintain the base rate applied to major monetary policy operations at the level of 2.65% per year (level set on November 6, 2020).
The average interest rates on the balance on loans in national currency increased by 0.1 percentage points, and on deposits - decreases. Average interest rates on loans and foreign currency deposits continued their downward trend.
As in the previous report, the forecasts for the evolution of the external environment show a gradual recovery of the world economy, in conditions of uncertainty, but without major risks. Both in the euro area and in the Russian Federation, economic growth is expected to be lower in 2021 and higher in 2022. At the same time, external pro-inflationary pressures will be more pronounced this year and lighter next year. In the current forecast round, currency projections have been adjusted for the appreciation of the US dollar and the depreciation of the euro and the Russian ruble. Projected increases in oil and food prices on foreign markets are significantly more pronounced in the current forecast round.
In the second quarter of this year, the annual inflation rate will reverse its trajectory and show an upward trend, reaching the inflation target at the end of the forecast horizon. During the first two consecutive quarters it will continue to position itself below the lower limit of the variation interval, but starting with the fourth quarter of 2021 it will return to the interval, being close to the target until the end of the forecast period.
The annual rate of core inflation will change in the first quarter of the forecast, thus increasing towards the end of the forecast horizon under the influence of the recovery of aggregate demand and the side effects generated by rising fuel prices. The annual rate of food prices will start a slight upward trend until the beginning of next year, after which it will vary slightly for the rest of the forecast period. The annual rate of regulated prices will increase sharply from the second half of the current year to the middle of next year, after which it will stabilize by the end of the forecast period. The annual rate of fuel prices will increase significantly in the first quarter. Subsequently, in the first half of next year, it will decrease rapidly until the second half of next year, increasing insignificantly towards the end of the forecast horizon.
Aggregate demand will continue to recover, although it will be disinflationary over the entire forecast horizon. The return of domestic aggregate demand will be influenced by the recovery of external demand, the improvement of monetary conditions and the recovery in agriculture this year.
Real monetary conditions will be restrictive during the first two consecutive quarters of the forecast horizon, having a negative impact on aggregate demand, then will be slightly stimulating.
The current forecast for inflation, compared to the previous inflation report, increased until the first quarter of 2022 and largely decreased for the rest of the comparable period2. The current forecast for core inflation has been revised downwards over the entire comparable period. The annual rate of food prices has been revised upwards until the first quarter of 2022 and downwards until the end of the comparable period. The current forecast for the annual rate of regulated prices has been revised downwards until the fourth quarter of 2021 and upwards for the rest of the comparable period. The forecast for the annual rate of fuel prices has been revised upwards until the first quarter of 2021 and downwards – for the rest of the comparable period.
1. IMF, World Economic Outlook April 2021
2. Quarter II 2021 – Quarter IV 2022


